Economics 9708/33 — May/June 2025
Cambridge A-Level · A Level Multiple Choice · answer key with instant marking and worked solutions
Topics Government Policies to Correct Market Failure · Macroeconomic Objectives and Policy Conflicts · Efficiency and Market Failure · Externalities, Social Costs and Benefits · Wage Determination and Labour Market Intervention · Employment and Unemployment · +14 more
Tap an option under each question to check it — your score builds as you go.
What is the equi-marginal principle?
Options
A As consumption of a product increases, the satisfaction from consumption of the product decreases by an equal amount.
B Consumers maximise utility where their marginal valuation for each product consumed is the same.
C The total satisfaction received by consumers from consumption of a product is constant.
D The marginal utility derived by consumers from the consumption of one more unit of a product is constant.
Working
The equi-marginal principle states that consumers maximise total utility by allocating their expenditure so that the marginal utility per dollar spent is equal across all goods. This implies that the marginal valuation (the price the consumer is willing to pay for the last unit) is the same for each product. Thus, option B is the correct definition.
Answer
B
B
Background Concept
The equi-marginal principle is a fundamental concept in consumer theory. It states that to maximise total utility from a given income, a consumer should allocate their spending so that the marginal utility per unit of currency (e.g., per dollar) is equal for all goods consumed. This is derived from the law of diminishing marginal utility: as consumption of a good increases, its marginal utility falls. The consumer will adjust purchases until the last unit of each good provides the same marginal utility per unit of expenditure.
Understanding the Question
This is a multiple-choice question asking for the correct definition of the equi-marginal principle. The options present different statements about marginal utility and total utility. The correct answer is the one that accurately describes the principle.
Approach
Read each option carefully. Recall the definition of the equi-marginal principle: consumers maximise utility when the marginal utility per dollar spent is equal across all goods. This is equivalent to saying that the marginal valuation (the price they are willing to pay for the last unit) is the same for each good. Option B states exactly this: "Consumers maximise utility where their marginal valuation for each product consumed is the same." The other options describe different concepts: A describes diminishing marginal utility, C describes constant total utility (false), and D describes constant marginal utility (false).
Step-by-Step Reasoning
- The equi-marginal principle is derived from the assumption that consumers aim to maximise total utility subject to a budget constraint.
- For two goods, the condition is: MU1 / P1 = MU2 / P2, where MU is marginal utility and P is price.
- This implies that the marginal valuation (the price the consumer is willing to pay for the last unit) is equal across goods. That is, the consumer's willingness to pay for the last unit of good 1 equals that for good 2.
- Option B: "Consumers maximise utility where their marginal valuation for each product consumed is the same." This directly matches the principle.
- Option A: "As consumption of a product increases, the satisfaction from consumption of the product decreases by an equal amount." This describes the law of diminishing marginal utility, but not the equi-marginal principle. It says "decreases by an equal amount" which is incorrect; marginal utility decreases but not necessarily by equal amounts.
- Option C: "The total satisfaction received by consumers from consumption of a product is constant." This is false; total utility increases with consumption, at a decreasing rate.
- Option D: "The marginal utility derived by consumers from the consumption of one more unit of a product is constant." This is false; marginal utility typically diminishes.
- Therefore, only option B is correct.
Key Takeaways
- The equi-marginal principle is a condition for utility maximisation: equalise marginal utility per dollar across goods.
- It is distinct from the law of diminishing marginal utility.
- The principle is fundamental to understanding consumer equilibrium.
Common Mistakes
- Confusing the equi-marginal principle with the law of diminishing marginal utility. The former is about allocation across goods; the latter is about the behavior of marginal utility as consumption of a single good increases.
- Thinking that the equi-marginal principle means marginal utilities are equal across goods (ignoring price differences). The condition is MU/P equality, not MU equality.
Things to Be Careful About
- The exact wording of the principle: it involves marginal utility per unit of expenditure, not just marginal utility.
- In multiple-choice questions, watch for options that describe related but different concepts.
The diagram shows the cost and revenue curves for a natural monopoly.
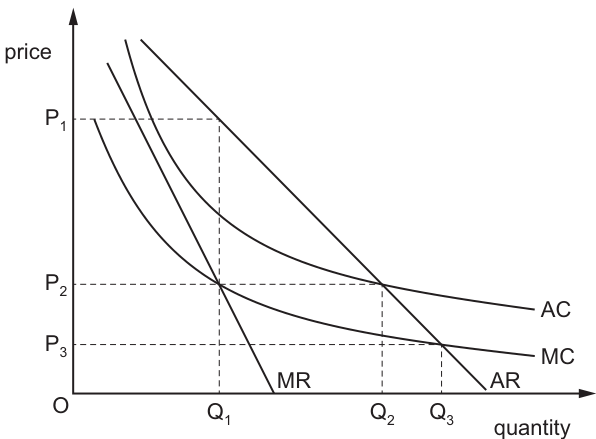
Which statement is correct?
Options
A P2 and Q2 will achieve both allocative efficiency and productive efficiency.
B P2 and Q1 will achieve productive efficiency but not allocative efficiency.
C P3 and Q3 will achieve allocative efficiency but not productive efficiency.
D P3 and Q3 will achieve both allocative efficiency and productive efficiency.
Reasoning
Allocative efficiency is achieved where price (equal to average revenue, AR) equals marginal cost (MC), as this ensures the marginal benefit to consumers equals the marginal cost of producing the final unit, maximising total social surplus. Productive efficiency is achieved at the output level where average cost (AC) is at its minimum, as this is the lowest possible cost per unit of output.
Applying these conditions to the provided natural monopoly diagram:
- The AR curve intersects the MC curve at quantity Q3 and price P3, so P3 and Q3 satisfy the allocative efficiency condition.
- The minimum point of the AC curve occurs at quantity Q2 and price P2, so productive efficiency is achieved at P2 and Q2, not at P3 and Q3.
Thus, P3 and Q3 achieve allocative efficiency but not productive efficiency, which matches option C.
Answer
C
C
Background Concept
A natural monopoly is a market structure where a single firm can supply the entire market demand at a lower average cost than any combination of multiple firms. This arises due to very high fixed costs and substantial economies of scale over the entire relevant range of output, meaning the average cost (AC) curve is downward-sloping across the entire market demand curve. Without regulation, a natural monopoly will maximise profit by producing where marginal revenue (MR) equals marginal cost (MC), charging a price above marginal cost and producing less than the socially efficient output.
Two key efficiency concepts are central to this question:
- Allocative efficiency: This occurs when the price consumers pay for a good (equal to their marginal benefit, represented by the average revenue (AR) curve) equals the marginal cost (MC) of producing that good. At this point, resources are allocated to their highest-valued use, and total social surplus (consumer surplus plus producer surplus) is maximised, with no deadweight loss.
- Productive efficiency: This occurs when a good is produced at the lowest possible average cost per unit. This is achieved at the minimum point of the average cost (AC) curve, where the firm is using the optimal combination of inputs to minimise per-unit production costs.
Understanding the Question
The question provides a cost and revenue diagram for a natural monopoly, with four labelled curves (AR, MR, AC, MC) and three price-quantity combinations (P1Q1, P2Q2, P3Q3). It asks the test-taker to identify which statement correctly describes whether each combination achieves allocative efficiency, productive efficiency, both, or neither. The task requires applying the formal definitions of the two efficiency types to the specific points on the diagram, rather than relying on general knowledge of monopoly outcomes. A common pitfall here is confusing the two efficiency conditions, as they refer to different points on the cost and revenue curves.
Approach
To solve this question, follow these steps:
- First, clearly recall the two distinct conditions for allocative and productive efficiency, so you do not mix them up.
- Locate each condition on the provided diagram:
- Find the intersection of the AR (demand) curve and the MC curve: this is the allocatively efficient point.
- Find the minimum point of the AC curve: this is the productively efficient point.
- Compare each option's stated price-quantity pair to these two points to determine which statement is accurate.
Step-by-Step Reasoning
- First, confirm the efficiency conditions:
- Allocative efficiency requires P = MC. Since AR represents the price consumers pay for each unit, the allocatively efficient point is where the AR curve crosses the MC curve.
- Productive efficiency requires output to be at the minimum of the AC curve, as this is the lowest possible average cost of production.
- Locate these points on the diagram:
- The AR curve (the downward-sloping curve furthest to the right, above the MR curve) intersects the MC curve (the lower downward-sloping curve) at quantity Q3 and price P3. This confirms P3Q3 is the allocatively efficient outcome.
- The AC curve (the upper downward-sloping curve, above MC) reaches its lowest point at quantity Q2, where the corresponding price is P2. This confirms P2Q2 is the productively efficient outcome.
- Evaluate each option against these findings:
- Option A claims P2Q2 achieves both efficiencies. While P2Q2 is productively efficient (at minimum AC), at Q2 the price P2 is above MC, so P≠MC, meaning it is not allocatively efficient. A is incorrect.
- Option B claims P2Q1 achieves productive efficiency but not allocative efficiency. Q1 is not the output at minimum AC, so P2Q1 is not productively efficient. B is incorrect.
- Option C claims P3Q3 achieves allocative efficiency but not productive efficiency. P3Q3 is where P=MC, so it is allocatively efficient. However, Q3 is greater than Q2 (the minimum AC output), so AC is higher than its minimum at Q3, meaning it is not productively efficient. C is correct.
- Option D claims P3Q3 achieves both efficiencies. As noted, P3Q3 is not productively efficient, as productive efficiency occurs at Q2. D is incorrect.
Key Takeaways
- The two core efficiency types have distinct, non-interchangeable conditions: allocative efficiency is P=MC, while productive efficiency is minimum AC. Always memorise these conditions precisely to avoid confusion.
- For a natural monopoly, the unregulated profit-maximising outcome (where MR=MC, at Q1 and P1) is neither allocatively nor productively efficient, which is the core rationale for regulating natural monopolies (e.g., setting price caps at the allocatively efficient level).
- When interpreting economics diagrams, always first identify each curve correctly, then locate the relevant intersection or extremum point before matching to answer options.
Common Mistakes
- Confusing the two efficiency conditions: many students incorrectly associate allocative efficiency with minimum AC, or productive efficiency with P=MC, leading them to select the wrong option.
- Misidentifying the curves: for example, mixing up AR and MR, or AC and MC, which would lead to locating the wrong intersection points. Remember that for a downward-sloping demand curve, MR lies below AR, and for a natural monopoly with economies of scale, MC lies below AC across the relevant output range.
- Assuming that the monopoly's profit-maximising point (MR=MC) is efficient: this point produces less than the allocatively efficient output and at a higher price, creating deadweight loss.
Things to Be Careful About
- Double-check the labels on the diagram: confirm which curve is AR (the demand curve, highest downward-sloping line), MR (below AR), AC (above MC, downward-sloping), and MC (lowest downward-sloping line) to avoid mislocating points.
- Confirm that you match the correct price to the correct quantity for each point: for example, P3 is the price at the AR=MC intersection, which corresponds to Q3, not Q2.
- Remember that for a natural monopoly, the AC curve is downward-sloping over the entire market demand range, so the minimum AC point is to the left of the allocatively efficient output (Q2 < Q3), meaning the productively efficient output is lower than the allocatively efficient output for this market structure.
What would not affect the budget line of an individual consumer?
Options
A the individual's preference for various goods
B the level of income tax
C the money prices of goods
D the incomes earned by the individual
Reasoning
The budget line shows the combinations of two goods that a consumer can afford given their money income and the prices of the goods. It is determined solely by the consumer's income and the prices of goods. Changes in income (including income tax) or prices shift or rotate the budget line. Preferences are represented by indifference curves, not the budget line. Therefore, a change in the individual's preferences does not affect the budget line.
Answer
A
A
Background Concept
A budget line illustrates all combinations of two goods that a consumer can purchase given a fixed income and given prices. Its equation is (P_x Q_x + P_y Q_y = M), where (P) are prices and (M) is money income. Any change in (M) or in a price changes the budget line. Indifference curves, on the other hand, represent the consumer's preferences – the subjective satisfaction from different bundles. The budget line is an objective constraint; preferences determine which point on the budget line the consumer chooses.
Understanding the Question
The question asks which of the four options does not affect the budget line. The correct answer must be something that influences the consumer’s choices but not the set of affordable bundles. The options are: (A) the individual’s preference for various goods, (B) the level of income tax, (C) the money prices of goods, (D) the incomes earned by the individual.
Approach
Recall that the budget line depends only on income (after taxes) and prices. Factors that change income or prices will shift or rotate the line. Anything else, such as tastes, affects where the consumer wants to be but not what they can afford.
Step-by-Step Reasoning
- Option A (preferences): Preferences are tastes. They determine the shape of indifference curves, not the budget line. The budget line remains unchanged if preferences change. This does not affect the budget line.
- Option B (income tax): Income tax reduces disposable income. A lower disposable income shifts the budget line inward (parallel shift if prices unchanged). Thus it does affect the budget line.
- Option C (money prices): A change in the price of a good rotates the budget line (pivot around the intercept of the other good). Clearly affects the budget line.
- Option D (incomes earned): A change in earned income directly changes total income, shifting the budget line. Affects the budget line.
Therefore, only A does not affect the budget line.
Key Takeaways
- The budget line is determined by income (including taxes and transfers) and prices.
- Preferences influence the consumer’s optimal choice but not the budget constraint itself.
- Always distinguish between the constraint (budget line) and the preferences (indifference curves).
Common Mistakes
- Confusing the budget line with the indifference curve: some students think that if a consumer likes a good more, the budget line shifts outwards. That is incorrect; more income, not more desire, shifts the line.
- Thinking that income tax does not affect the budget line because it is not “income” but a deduction: but tax lowers disposable income, so it does shift the budget line.
- Forgetting that the budget line is an “objective” constraint – it depends on prices and the actual money available, not on subjective valuation.
Things to Be Careful About
- Read “would not affect” carefully; it selects the factor that leaves the budget line unchanged.
- Remember that the budget line is a straight line (given constant prices), and its position is completely described by the intercepts. Anything altering the intercepts is an affecting factor.
- Preferences affect the demand curve, not the budget constraint.
The diagram shows the marginal private costs (MPC) and marginal private benefits (MPB) of a product. Consumers initially estimate that marginal private costs are at MPC1 and marginal private benefits are at MPB1.
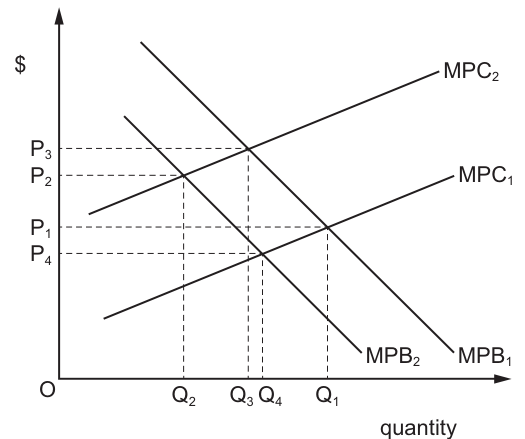
What is the impact on the market demand for the product if the consumer realises they have underestimated the MPC of buying the product but not the MPB?
Options
A The consumer underconsumes the product by Q1Q2.
B The consumer underconsumes the product by Q1Q3.
C The consumer overconsumes the product by Q1Q3.
D The consumer overconsumes the product by Q1Q4.
Working
The initial consumer equilibrium occurs where the perceived marginal private cost (MPC1) equals marginal private benefit (MPB1), which corresponds to quantity Q1 on the diagram.
When the consumer realises they have underestimated MPC, the actual MPC curve shifts left from MPC1 to MPC2 (higher marginal cost at every quantity level). The MPB remains unchanged at MPB1, as the consumer did not misestimate this.
The new true private equilibrium is at the intersection of MPC2 and MPB1, which corresponds to quantity Q3.
Since Q3 is less than the initial quantity Q1, the consumer is consuming more than the optimal quantity: this is overconsumption. The magnitude of overconsumption is the difference between Q1 and Q3, which is Q1Q3.
Answer
C
C
Background Concept
Marginal private cost (MPC) is the additional cost a consumer incurs from purchasing one extra unit of a good, while marginal private benefit (MPB) is the additional benefit a consumer gains from consuming one extra unit. A rational consumer maximises their private welfare by choosing the quantity where their perceived MPC equals their MPB, as this is the point where the extra benefit of the last unit consumed exactly matches its extra cost.
If a consumer misestimates their MPC, their perceived optimal quantity will differ from the true optimal quantity, which is where the actual MPC equals the actual MPB. Overconsumption occurs when the quantity a consumer actually chooses is higher than the true optimal quantity: this means units are being consumed where the actual marginal cost exceeds the marginal benefit, reducing total welfare. Underconsumption is the opposite, where the chosen quantity is below the true optimal, so units with marginal benefit higher than marginal cost are not consumed.
Understanding the Question
The question provides a diagram with two upward-sloping MPC curves (MPC1 and MPC2, where MPC2 is to the left of MPC1, meaning higher marginal costs at every quantity) and two downward-sloping MPB curves (MPB1 and MPB2, with MPB2 to the left of MPB1). The consumer initially believes their MPC is MPC1 and their MPB is MPB1, so their initial consumption choice is at the intersection of these two curves, corresponding to quantity Q1. The question states the consumer later realises they underestimated MPC (so actual MPC is the higher MPC2) but did not underestimate MPB (so MPB remains at MPB1). We need to determine whether the consumer over or underconsumes, and by how much, measured as the difference between the initial quantity Q1 and the new true equilibrium quantity.
Approach
First, identify the initial equilibrium quantity from the intersection of the perceived MPC (MPC1) and MPB (MPB1), which is Q1. Next, identify the new true equilibrium quantity from the intersection of the actual MPC (MPC2) and the unchanged MPB (MPB1), which is Q3 from the diagram. Compare the two quantities: since Q1 is larger than Q3, the consumer is consuming more than the true optimal quantity, so this is overconsumption. The magnitude of overconsumption is the difference between Q1 and Q3, which is Q1Q3. We can eliminate incorrect options first: underconsumption options (A and B) are impossible because the optimal quantity fell, so the original higher quantity is too large, not too small. Option D uses the wrong magnitude (Q1Q4 instead of Q1Q3), leaving C as the only valid choice.
Step-by-Step Reasoning
- Initial perceived equilibrium: The consumer initially thinks their marginal private cost is MPC1, and their marginal private benefit is MPB1. A rational consumer chooses the quantity where perceived MPC equals MPB, which is the intersection of MPC1 and MPB1. From the diagram, this intersection corresponds to quantity Q1 on the horizontal axis, so the consumer initially chooses to consume Q1.
- Revision of MPC: The consumer realises they underestimated MPC, meaning the actual marginal cost of each unit is higher than they thought. This is represented by a leftward shift of the MPC curve from MPC1 to MPC2: a leftward shift of an upward-sloping curve means higher marginal costs at every quantity level.
- New true equilibrium: The consumer did not underestimate MPB, so the MPB curve remains at MPB1. The true private optimum is now where actual MPC (MPC2) equals actual MPB (MPB1). The intersection of MPC2 and MPB1 on the diagram corresponds to quantity Q3, which is lower than Q1 (since Q3 is to the left of Q1 on the quantity axis).
- Determine over/underconsumption: The consumer is still consuming Q1 (their original choice, based on their earlier misperception), but the true optimal quantity is Q3. Since Q1 > Q3, the consumer is consuming more than the optimal quantity: this is overconsumption, as all units between Q3 and Q1 have an actual marginal cost higher than their marginal benefit, so they should not be consumed.
- Magnitude of overconsumption: The amount of overconsumption is the difference between the consumed quantity (Q1) and the optimal quantity (Q3), which is Q1 - Q3, written as Q1Q3 in the answer options.
- Eliminate incorrect options: Options A and B refer to underconsumption, which is incorrect because the consumed quantity is higher than the optimum. Option D refers to an overconsumption of Q1Q4, but Q4 is not the true equilibrium quantity (the intersection of MPC2 and MPB1 is at Q3, not Q4, which is the intersection of MPC1 and MPB2), so D is wrong. The correct answer is C.
Key Takeaways
- The optimal consumption quantity for a consumer is where actual MPC equals actual MPB. Misestimating MPC leads to a deviation from this optimal quantity.
- A leftward shift of the upward-sloping MPC curve (higher costs at each quantity) reduces the optimal consumption quantity, ceteris paribus.
- If a consumer underestimates their MPC, they will consume more than the true optimal quantity, leading to overconsumption, as they purchase units where the actual marginal cost exceeds the marginal benefit.
- When reading diagrams, always confirm the order of quantities on the horizontal axis: a position farther to the right corresponds to a higher quantity.
Common Mistakes
- Confusing a shift in MPC with a movement along the curve: a change in the consumer's perception of MPC is a shift of the entire curve, not a movement along it, as it affects the cost of every unit, not just the marginal unit.
- Mixing up over and underconsumption: overconsumption occurs when quantity is above the optimal level, underconsumption when it is below. Since the MPC shift reduces the optimal quantity, the original higher quantity is overconsumption, not under.
- Misreading the diagram's quantity labels: Q1 is the largest quantity (farthest right on the x-axis), Q2 is the smallest, so Q1 > Q3 > Q4 > Q2. Confusing the order of these labels leads to picking the wrong magnitude (e.g. Q1Q4 instead of Q1Q3).
- Forgetting that MPB is unchanged: the question explicitly states the consumer did not underestimate MPB, so the MPB curve does not shift, meaning the new equilibrium is at the intersection of MPC2 and MPB1, not MPB2.
Things to Be Careful About
- Always confirm the direction of curve shifts: an upward-sloping MPC curve shifting left means higher marginal costs at every quantity, not lower.
- The difference between two quantities is the absolute value of their subtraction: since Q1 > Q3, the overconsumption is Q1 - Q3, written as Q1Q3 in the options.
- Ensure your answer matches the question's focus: the question asks about the impact on consumption (over/under and magnitude), not on price, consumer surplus or producer surplus, so focus only on the quantity comparison.
- For MCQs, eliminate wrong options first to narrow down choices: A and B are underconsumption (impossible here), D has the wrong magnitude, so C is the only valid answer.
What is an internal economy of scale?
Options
A efficient local transport networks
B improved access to spare parts as a result of industry growth
C lower risks from supplying a wider range of customers
D the training of skilled labour at a college financed by local firms
Answer
An internal economy of scale is a cost advantage that arises from the growth of the firm itself. Option C is correct because spreading risk over a wider range of customers reduces the average cost of holding inventories and managing credit, and this benefit is generated by the firm's own expansion, not by the growth of the industry as a whole.
Answer
C
C
Background Concept
Economies of scale are reductions in long-run average cost (LRAC) that occur as a firm increases its scale of production. They are categorised into two types:
- Internal economies of scale: cost savings that arise from the growth of the individual firm itself. They are under the firm's own control and include technical, managerial, financial, marketing, and risk-bearing economies.
- External economies of scale: cost savings that benefit all firms in an industry as the industry as a whole expands. These arise from factors outside any single firm, such as a larger pool of skilled labour, specialised suppliers, or improved infrastructure.
Understanding the Question
This is a multiple-choice question asking for the correct example of an internal economy of scale. The four options present different scenarios, and the task is to identify which one describes a cost advantage that comes from the firm's own growth rather than from industry-wide developments.
Approach
For each option, determine whether the cost advantage described is generated by the expansion of the individual firm (internal) or by the expansion of the whole industry (external). The correct answer will be the one where the benefit is clearly a result of the firm's own increased size.
Step-by-Step Reasoning
- Option A: Efficient local transport networks. These are a benefit that arises when many firms locate in the same area, leading to better infrastructure. This is an external economy of scale because it depends on the growth of the industry or region, not on the growth of a single firm.
- Option B: Improved access to spare parts as a result of industry growth. This is also an external economy — as the industry expands, more suppliers emerge, making spare parts more readily available for all firms. The individual firm does not create this benefit by its own expansion.
- Option C: Lower risks from supplying a wider range of customers. This is a classic internal economy of scale known as a risk-bearing economy. As a firm grows, it can diversify its customer base, so the failure of any single customer has a smaller impact on total revenue. This reduces the average cost of risk (e.g., lower bad-debt provisions, less need for precautionary inventory). The benefit is generated entirely by the firm's own growth.
- Option D: The training of skilled labour at a college financed by local firms. This is an external economy — the college is funded collectively by firms in the area, and all of them benefit from the trained workforce. No single firm's expansion alone creates this advantage.
Therefore, only Option C describes an internal economy of scale.
Key Takeaways
- The key distinction is the source of the cost reduction: internal = from the firm's own growth; external = from the growth of the industry or economy.
- Common examples of internal economies: technical (larger machines), managerial (specialisation), financial (better borrowing rates), marketing (bulk advertising), and risk-bearing (diversification).
- Common examples of external economies: skilled labour pools, specialised suppliers, improved infrastructure, and knowledge spillovers.
Common Mistakes
- Confusing external economies (industry-wide benefits) with internal ones. Options A, B, and D are all plausible-sounding but are external.
- Thinking that any benefit that reduces costs must be internal. The question tests whether the student can identify the source of the benefit.
Things to Be Careful About
- Read each option carefully and ask: "Does this benefit arise because this firm has grown, or because the whole industry has grown?"
- Remember that internal economies are under the firm's own control; external economies are not.
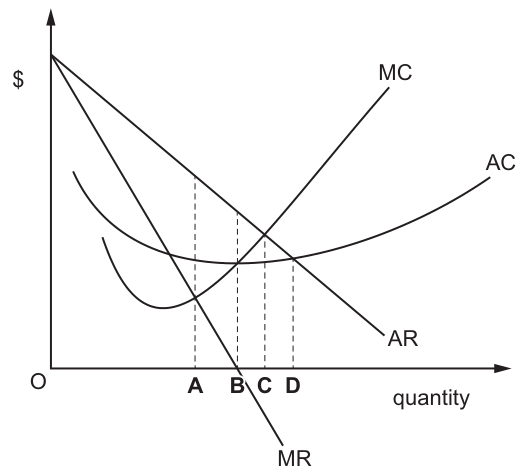
The diagram shows the costs and revenue for a monopoly.
Which level of output would produce only a normal profit?
Options
A output level A on Fig. 6.1
B output level B on Fig. 6.1
C output level C on Fig. 6.1
D output level D on Fig. 6.1
Answer
Normal profit occurs where total revenue equals total cost, meaning average revenue (AR) equals average cost (AC). On the diagram, this condition is satisfied at output level D, where the AR curve intersects the AC curve. At this output, the firm makes zero economic profit (normal profit).
Output level A is where MR = 0 (revenue maximisation). Output level B is where MC = MR (profit maximisation). Output level C is where MC = AR (allocative efficiency). Only at output D does AR = AC, indicating normal profit.
Therefore, the correct option is D.
D
Background Concept
Normal profit is the minimum profit required to keep a firm operating in its current industry in the long run. It occurs when total revenue (TR) exactly equals total cost (TC), meaning the firm is covering all its explicit costs plus its implicit (opportunity) costs. In diagrammatic terms, normal profit is achieved where average revenue (AR) equals average cost (AC), i.e., AR = AC. At this point, economic profit is zero.
In a monopoly market structure, the firm faces a downward-sloping average revenue (AR) curve (the demand curve) and a marginal revenue (MR) curve that lies below it. The marginal cost (MC) curve is typically upward-sloping, and the average cost (AC) curve is U-shaped, with MC intersecting AC at its minimum point.
Understanding the Question
This is a 1-mark multiple-choice question presenting a standard monopoly diagram with four labeled output levels (A, B, C, D) on the horizontal axis. The question asks which output level would produce only a normal profit. The diagram shows the intersection points of the cost and revenue curves that correspond to different economic concepts: revenue maximisation, profit maximisation, allocative efficiency, and the break-even (normal profit) point.
Approach
The key is to recall that normal profit means zero economic profit, which occurs where AR = AC. The strategy is to locate the point on the diagram where the AR curve intersects the AC curve. This intersection represents the output level at which the firm is just covering its total costs, earning only normal profit.
Step-by-Step Reasoning
Let us examine each output level marked on the diagram:
-
Output level A: This is where the MR curve intersects the horizontal axis (MR = 0). This represents revenue maximisation, where the firm produces the output that maximises total revenue. At this output, the price (AR) is above the AC curve, so the firm would be making supernormal profit, not normal profit.
-
Output level B: This is where the MC curve intersects the MR curve (MC = MR). This is the profit-maximising output for a monopolist. At this quantity, if the AR curve lies above the AC curve (which it does in the diagram), the firm earns supernormal profit. This is not normal profit.
-
Output level C: This is where the MC curve intersects the AR curve (MC = AR). This represents allocative efficiency, where price equals marginal cost. While this is an efficient outcome, the AC curve lies below the AR curve at this point, meaning the firm still earns supernormal profit. This is not the normal profit condition.
-
Output level D: This is where the AR curve intersects the AC curve (AR = AC). At this output level, total revenue equals total cost. The firm is breaking even in economic terms, earning only normal profit (zero economic profit). This is the correct answer.
Key Takeaways
- Normal profit (zero economic profit) occurs where AR = AC.
- On a monopoly diagram, locate the intersection of the AR and AC curves to find the normal profit output.
- Output B (MC = MR) is profit maximisation, which typically yields supernormal profit for a monopolist.
- Output C (MC = AR) is allocative efficiency.
- Output A (MR = 0) is revenue maximisation.
- Output D (AR = AC) is the break-even point where only normal profit is earned.
Common Mistakes
- Choosing B: Students often confuse profit maximisation with normal profit. At the profit-maximising output (MC = MR), a monopolist typically earns supernormal profit because AR > AC.
- Choosing C: Students may confuse allocative efficiency (MC = AR) with normal profit. Allocative efficiency concerns resource allocation, not the profit level.
- Choosing A: Students may incorrectly associate MR = 0 with break-even, but this is simply revenue maximisation.
- Misreading the diagram: Failing to distinguish which curve is which, particularly confusing the AC and MC curves or the AR and MR curves.
Things to Be Careful About
- Always verify which curve is which: AR is the flatter downward-sloping line (the demand curve), while MR is the steeper one below it. AC is U-shaped, and MC is the upward-sloping curve that cuts AC at its minimum.
- Normal profit is not the same as supernormal profit. Normal profit means zero economic profit, whereas supernormal profit means AR > AC.
- The condition AR = AC is the precise definition of normal profit; do not confuse it with MC = AR or MC = MR.
- In monopoly, because the firm has market power, the profit-maximising output (B) usually results in supernormal profit, not normal profit.
Which combination of statements about small firms and large firms is most likely to be correct?
Options
| small firms | large firms | |
|---|---|---|
| A | are more common in manufacturing than in services | face high barriers to exit |
| B | are more numerous than large firms | do not experience diseconomies of scale |
| C | can do well when each item produced is different | may arise from internal growth or mergers |
| D | cannot have any monopoly power | cannot earn supernormal profits |
Answer
Option C is correct. Small firms often thrive in markets where products are customised or differentiated, as they can offer flexibility and personal service. Large firms can grow through internal expansion (organic growth) or through mergers and takeovers (external growth). The other options contain incorrect statements: A is wrong because small firms are more common in services than manufacturing; B is wrong because large firms can experience diseconomies of scale; D is wrong because small firms can have monopoly power in a local or niche market, and large firms can earn supernormal profits.
Answer
C
C
Background Concept
Firms vary in size from small sole traders to large multinational corporations. Small firms are typically more numerous, often operate in service sectors (e.g., retail, hospitality, professional services), and can succeed by offering customised or niche products. Large firms benefit from economies of scale, which reduce average costs, but may face diseconomies of scale as they grow (e.g., coordination problems, bureaucracy). Large firms can arise through internal growth (reinvesting profits) or external growth (mergers and takeovers). Both small and large firms can possess monopoly power in certain contexts: a small firm may be the only provider in a local area, while a large firm may dominate a national market. Supernormal profits are possible for any firm with market power, regardless of size.
Understanding the Question
This multiple-choice question asks you to identify which combination of statements about small firms and large firms is most likely to be correct. Each option pairs a statement about small firms with a statement about large firms. You must evaluate the truth of each statement based on economic principles. The correct option is the one where both statements are accurate.
Approach
Evaluate each statement in the four options systematically. Use your knowledge of:
- The distribution of firms by size across sectors.
- Economies and diseconomies of scale.
- Market power and monopoly.
- Methods of firm growth.
Check both statements in each option. If either statement is false, the option is incorrect. Only option C has two true statements.
Step-by-Step Reasoning
Option A:
- Statement about small firms: "are more common in manufacturing than in services." This is false. Small firms are more common in services (e.g., hairdressers, cafes, consultants) because manufacturing often requires significant capital investment and economies of scale, favouring larger firms.
- Statement about large firms: "face high barriers to exit." This is not generally true. Large firms may face high exit barriers due to sunk costs (e.g., specialised machinery), but small firms can also face barriers (e.g., lease obligations). The statement is too broad and not a defining characteristic. Therefore, Option A is incorrect.
Option B:
- Statement about small firms: "are more numerous than large firms." This is true. In most economies, the vast majority of firms are small (e.g., over 99% of firms in the UK are small or medium-sized).
- Statement about large firms: "do not experience diseconomies of scale." This is false. Large firms often experience diseconomies of scale as they grow beyond a certain size, leading to rising average costs due to inefficiencies. Therefore, Option B is incorrect.
Option C:
- Statement about small firms: "can do well when each item produced is different." This is true. Small firms can thrive in markets requiring customisation or differentiation (e.g., bespoke furniture, specialised software). They can offer flexibility and personal service that large firms may struggle to provide.
- Statement about large firms: "may arise from internal growth or mergers." This is true. Large firms can grow organically by reinvesting profits (internal growth) or through mergers and takeovers (external growth). Both are common paths to becoming large.
- Both statements are correct, so Option C is the correct answer.
Option D:
- Statement about small firms: "cannot have any monopoly power." This is false. A small firm can have monopoly power in a local market (e.g., the only grocery store in a remote village) or in a niche market (e.g., a patent on a specialised component). Monopoly power is about market control, not absolute size.
- Statement about large firms: "cannot earn supernormal profits." This is false. Large firms with market power (e.g., monopolies or oligopolies) can earn supernormal profits in the short run and sometimes in the long run if barriers to entry exist.
- Therefore, Option D is incorrect.
Thus, only Option C contains two true statements.
Key Takeaways
- Small firms are numerous and often found in service sectors; they can succeed through customisation and niche markets.
- Large firms can achieve economies of scale but may face diseconomies; they can grow internally or through mergers.
- Both small and large firms can have monopoly power and earn supernormal profits under certain conditions.
- When evaluating multiple statements, check each one independently; an option is only correct if both statements are accurate.
Common Mistakes
- Assuming small firms cannot have monopoly power. In reality, monopoly power depends on market definition, not firm size.
- Believing large firms always experience diseconomies of scale. Diseconomies are possible but not inevitable; some large firms manage to avoid them.
- Thinking small firms are more common in manufacturing. In fact, services dominate small firm activity.
- Overlooking that both statements in an option must be true; a single false statement makes the entire option incorrect.
Things to Be Careful About
- Read each statement precisely. For example, "cannot have any monopoly power" is an absolute; one counterexample disproves it.
- Distinguish between general tendencies and absolute claims. Most statements in this question are generalisations, so consider typical cases.
- Remember that large firms can arise from both internal and external growth; do not assume only one method is possible.
- In multiple-choice questions, eliminate clearly false options first to narrow down choices.
Good X is a popular product that creates a negative externality when it is consumed.
The government wants to reduce the consumption of good X significantly.
Under which circumstances is the government most likely to meet its aim?
Options
| government policy | price elasticity of demand for good X | |
|---|---|---|
| A | subsidy | more than 1 |
| B | subsidy | less than 1 |
| C | indirect tax | more than 1 |
| D | indirect tax | less than 1 |
Reasoning
To reduce consumption of a good that creates a negative externality, the government should impose an indirect tax to internalise the externality. A subsidy would lower the price and increase consumption, so options A and B are incorrect.
The effectiveness of an indirect tax in reducing consumption depends on the price elasticity of demand (PED). If demand is elastic (PED > 1), the percentage fall in quantity demanded is greater than the percentage rise in price, leading to a significant reduction in consumption. If demand is inelastic (PED < 1), the reduction is smaller.
Therefore, the government is most likely to meet its aim of significantly reducing consumption by imposing an indirect tax on a good with elastic demand.
Answer
C
C
Background Concept
A negative externality of consumption occurs when the consumption of a good imposes costs on third parties that are not reflected in the market price. This leads to overconsumption because the private benefit exceeds the social benefit. To correct this market failure, the government can impose an indirect tax equal to the external cost, which raises the price and reduces consumption to the socially optimal level.
Price elasticity of demand (PED) measures the responsiveness of quantity demanded to a change in price. It is calculated as the percentage change in quantity demanded divided by the percentage change in price. Demand is elastic if PED > 1 (quantity changes proportionally more than price), and inelastic if PED < 1 (quantity changes proportionally less).
Understanding the Question
The question asks for the combination of government policy and demand elasticity that most likely achieves a significant reduction in consumption of a good with a negative externality. The options pair a policy (subsidy or indirect tax) with a PED condition (elastic or inelastic). We need to select the one that will reduce consumption the most.
Approach
First, eliminate policies that would increase consumption (subsidy). Then, among tax options, compare the effect of elastic vs inelastic demand on the quantity reduction. Use the concept that a given price increase leads to a larger quantity reduction when demand is elastic.
Step-by-Step Reasoning
- Negative externality of consumption: The social cost exceeds private cost, so the free market overproduces and overconsumes. To reduce consumption, the government can impose a tax equal to the external cost, shifting the supply curve left (or increasing price).
- A subsidy would lower the price and encourage more consumption, which is opposite to the aim. So A and B are wrong.
- An indirect tax raises the price. The extent to which quantity falls depends on PED.
- If PED > 1 (elastic), a given % price rise leads to a larger % fall in quantity. So consumption falls significantly.
- If PED < 1 (inelastic), quantity falls by a smaller % than the price rise, so the reduction is less significant.
- Therefore, to achieve a significant reduction, the government should impose an indirect tax on a good with elastic demand. That is option C.
Key Takeaways
- To correct a negative externality of consumption, a tax is appropriate; a subsidy would worsen the problem.
- The effectiveness of a tax in reducing quantity depends on the price elasticity of demand: more elastic demand leads to a larger reduction.
- When evaluating policy effectiveness, always consider the responsiveness of consumers.
Common Mistakes
- Choosing a subsidy because it might be seen as a way to reduce consumption? No, subsidy reduces price and increases consumption.
- Thinking that inelastic demand leads to a larger reduction: actually, inelastic demand means quantity is less responsive, so the reduction is smaller.
- Confusing the effect on price and quantity: a tax raises price, but the quantity effect depends on elasticity.
Things to Be Careful About
- Remember that a negative externality of consumption means the good is overconsumed; the policy should reduce consumption.
- PED is defined as % change in quantity / % change in price; elastic means absolute value > 1.
- The question asks for "most likely to meet its aim" – significant reduction, so elastic demand is key.
A government introduces tradeable pollution permits to reduce pollution.
What is an advantage of this scheme?
Options
A It allows consumers to determine the optimum pollution level.
B It can provide rewards for firms that reduce pollution.
C It enables the government to raise revenue from the resale of permits.
D It uses the market system with no administrative costs.
Tradeable pollution permits create a market for the right to pollute. The government sets a total cap on pollution and issues permits equal to that cap. Firms that can reduce pollution at low cost will do so and sell their surplus permits to firms facing higher abatement costs. This provides a financial reward for firms that reduce pollution, as they can profit from selling permits. Option B correctly identifies this advantage.
Option A is incorrect because the government, not consumers, determines the total pollution level by setting the cap. Option C is incorrect: the government may raise revenue initially by auctioning permits, but the resale of permits between firms does not generate government revenue. Option D is incorrect because the scheme involves administrative costs for monitoring, enforcement, and managing the permit market.
Answer
B
B
Background Concept
Tradeable pollution permits (also called cap-and-trade) are a market-based policy to correct the negative externality of pollution. The government sets a maximum allowable level of pollution (the cap) and issues permits equal to that cap. Firms must hold permits for each unit of pollution they emit. Permits can be bought and sold among firms. This creates a market price for pollution, internalising the externality. The key advantage is that it achieves the pollution reduction at the lowest possible cost because firms with low abatement costs reduce pollution and sell permits, while firms with high abatement costs buy permits instead of reducing. This cost-effectiveness is the main economic advantage.
Understanding the Question
The question asks for an advantage of a tradeable pollution permit scheme. It is a multiple-choice question with four options. The correct answer is the one that accurately describes a benefit of such a scheme. The distractors are common misconceptions: that consumers determine the pollution level, that the government raises revenue from resale, or that there are no administrative costs.
Approach
To identify the correct answer, recall the purpose and mechanism of tradeable permits. The scheme is designed to reduce pollution efficiently by using market forces. The advantage is that it provides incentives for firms to reduce pollution because they can profit from selling permits. Evaluate each option against this understanding.
Step-by-Step Reasoning
- Option A: "It allows consumers to determine the optimum pollution level." This is false. The government sets the total cap on pollution, not consumers. Consumers may influence demand for goods that cause pollution, but they do not directly determine the pollution level under a permit scheme.
- Option B: "It can provide rewards for firms that reduce pollution." This is correct. Firms that reduce pollution below their permit holdings can sell the excess permits, earning revenue. This financial reward incentivises pollution reduction.
- Option C: "It enables the government to raise revenue from the resale of permits." This is misleading. The government may raise revenue if it auctions permits initially, but the resale of permits between firms does not generate government revenue. The phrase "resale of permits" typically refers to secondary market transactions among firms, not government sales.
- Option D: "It uses the market system with no administrative costs." This is false. While the scheme uses market forces, it still requires administrative costs for monitoring emissions, enforcing compliance, and managing the permit registry. There are always some administrative costs.
Thus, option B is the only correct advantage.
Key Takeaways
- Tradeable pollution permits combine government intervention (setting the cap) with market mechanisms (trading) to reduce pollution efficiently.
- The main advantage is cost-effectiveness: pollution reduction occurs where it is cheapest, and firms have a financial incentive to reduce emissions.
- Common misconceptions include thinking that consumers determine the pollution level, that the government profits from resale, or that there are no administrative costs.
Common Mistakes
- Choosing option C because of confusion between initial auction revenue and secondary market resale. The question specifically says "resale of permits", which is between firms, not government revenue.
- Choosing option D because of the idea that market-based policies have no costs. In reality, any regulatory scheme has administrative costs.
- Misunderstanding the role of consumers: in a permit scheme, the government sets the cap, not consumers.
Things to Be Careful About
- Read the wording carefully: "resale of permits" implies secondary market, not initial auction.
- Remember that tradeable permits are a form of market-based regulation, but they still require government oversight and incur administrative costs.
- The advantage is about incentives for firms, not about consumer sovereignty or zero costs.
To reduce traffic congestion, a government built a new highway. A majority of the citizens were opposed to this. Some citizens responded by switching from public transport to private cars. This caused car journeys to take even longer.
What can be concluded about government failure in this case?
Options
A It occurred because the government's opportunity costs were not considered.
B It occurred because the wishes of the majority of citizens were ignored.
C It occurred because the result was unintended.
D It occurred from over-reliance on the market system.
Reasoning
Government failure occurs when government intervention leads to an outcome that is worse than the original market failure, often due to unintended consequences. In this case, the policy intended to reduce congestion but instead increased it because citizens switched from public transport. This unintended outcome is a classic example of government failure.
Answer
C
C
Background Concept
Government failure refers to a situation where government intervention in the economy leads to a net welfare loss or an outcome that is worse than the original market failure. It can arise from various causes, including unintended consequences, information problems, administrative costs, and the influence of special interest groups. Unintended consequences occur when the actual outcome of a policy is different from what was intended, often because economic agents change their behaviour in response to the policy. This is a key concept in assessing the effectiveness of government intervention.
Understanding the Question
The scenario describes a government building a new highway to reduce traffic congestion. Despite majority opposition, the policy was implemented. Citizens responded by switching from public transport to private cars, which caused car journeys to take even longer. The question asks: what can be concluded about government failure in this case? Each option offers a different reason: A says opportunity costs were not considered; B says the wishes of the majority were ignored; C says the result was unintended; D says there was over-reliance on the market system. We need to identify which statement correctly describes the type of government failure present.
Approach
First, recall the definition of government failure and its common causes. Then, examine the scenario carefully: the government's intention was to reduce congestion, but the outcome was the opposite. This is a clear case of an unintended consequence. Evaluate each option against this observation: A is about opportunity cost, but the scenario does not provide evidence that the government failed to consider opportunity cost; B is about ignoring majority wishes, but government failure is not defined by public opinion; D is about over-reliance on the market, but the government actually intervened (built a highway), so it is not a case of relying on the market. Only C directly matches the unintended outcome.
Step-by-Step Reasoning
- Identify the government action: The government built a new highway to reduce traffic congestion. This is a supply-side intervention aimed at increasing road capacity.
- Identify the outcome: Instead of reducing congestion, car journeys took even longer. This is because some citizens switched from public transport to private cars, increasing the number of cars on the road.
- Compare intended vs actual: The intended effect was to reduce congestion; the actual effect was to increase it. This is an unintended consequence.
- Evaluate option A: 'Opportunity costs were not considered.' The scenario does not mention whether the government considered alternative uses of the funds. While opportunity cost is a relevant concept, it is not the primary reason for the failure here; the failure is about the behavioural response, not about the cost of the project.
- Evaluate option B: 'The wishes of the majority of citizens were ignored.' The fact that a majority opposed the highway does not in itself constitute government failure. Government failure is about economic inefficiency, not about democratic preferences. A policy that ignores majority opinion but still achieves its goal may not be government failure; conversely, a policy that follows majority opinion but leads to welfare loss is government failure. So this is not the correct conclusion.
- Evaluate option C: 'It occurred because the result was unintended.' This is directly supported by the scenario: the government intended to reduce congestion, but the result was increased congestion. The behavioural response (switching from public transport to cars) was not anticipated, leading to a worse outcome. This is a classic example of government failure due to unintended consequences.
- Evaluate option D: 'Over-reliance on the market system.' The government intervened by building the highway, so it did not rely on the market. If anything, the failure arose from the intervention itself, not from a lack of intervention. So this is incorrect.
- Conclusion: The correct answer is C, as the failure occurred because the outcome was unintended.
Key Takeaways
- Government failure occurs when intervention leads to a net welfare loss, often due to unintended consequences, information problems, or administrative costs.
- Unintended consequences are a common cause of government failure: policies change behaviour in ways not anticipated by policymakers.
- When evaluating multiple-choice options, always match the scenario to the specific definition or cause of failure. Avoid selecting options that are plausible but not directly supported by the evidence.
- The fact that a policy is unpopular does not mean it is government failure; economic efficiency is the relevant criterion.
Common Mistakes
- Confusing government failure with market failure: the scenario describes a government intervention that made things worse, not a market failure that the government failed to correct.
- Thinking that any opposition or unpopular decision is government failure: government failure is about economic outcomes, not political popularity.
- Selecting option A because 'opportunity cost' is an important economic concept, but the scenario does not provide evidence that the government ignored opportunity cost. The failure is in the behavioural response, not in the cost-benefit analysis.
- Assuming that because the government intervened, the failure must be due to over-reliance on the market: in fact, the intervention itself caused the problem.
Things to Be Careful About
- Read the scenario carefully: the key is that the outcome was the opposite of what was intended. That is the hallmark of an unintended consequence.
- Distinguish between different causes of government failure: unintended consequences, rent-seeking, information asymmetry, etc. In this case, the cause is clearly unintended consequences.
- Do not bring in extra assumptions not given in the scenario. For example, we do not know if the government considered opportunity costs, so we cannot conclude that they did not.
- Remember that government failure is a concept that requires the outcome to be worse than the original market failure. Here, the congestion became worse, so it is a clear case of government failure.
What could result in an individual being caught in the poverty trap if their income increases?
Options
A national minimum wage is changed
B benefits payments are means-tested
C subsidised housing payments for low-income earners are increased
D the income level at which income tax is first paid is increased
Reasoning
The poverty trap occurs when an increase in gross income leads to a reduction in means-tested benefits, so net income rises little or falls, creating a disincentive to work. Option B, 'benefits payments are means-tested', directly describes this mechanism: as income rises, means-tested benefits are withdrawn, potentially trapping the individual. Option A changes the wage floor but does not directly cause the trap. Option C increases subsidised housing payments, which would increase net income and reduce the trap. Option D raises the tax-free threshold, also increasing net income. Therefore, B is correct.
Answer
B
B
Background Concept
The poverty trap is a situation where an increase in a person's gross income leads to a reduction in means-tested benefits and an increase in taxes, so that net income rises very little or even falls. This creates a disincentive to increase earnings through work, as the individual gains little or nothing financially. Means-tested benefits are payments that depend on the recipient's income or wealth; as income rises, the benefit amount is reduced. Common examples include housing benefits, income support, and tax credits.
Understanding the Question
The question asks which of the four options could result in an individual being caught in the poverty trap if their income increases. It is testing the understanding of the mechanism behind the poverty trap: the withdrawal of means-tested benefits as income rises. The correct answer is the one that describes a policy that directly causes this withdrawal.
Approach
To answer, recall the definition of the poverty trap. Then evaluate each option:
- A: National minimum wage change affects the wage floor, not the withdrawal of benefits.
- B: Means-tested benefits are exactly the type of benefits that are reduced as income rises, causing the trap.
- C: Increasing subsidised housing payments for low-income earners would increase their net income, reducing the trap.
- D: Increasing the income tax threshold reduces the tax burden, increasing net income, reducing the trap.
Thus, only B fits.
Step-by-Step Reasoning
- Define the poverty trap: It occurs when an increase in gross income leads to a reduction in means-tested benefits and/or an increase in taxes, so net income does not increase proportionally or may even decrease.
- Option A: Changing the national minimum wage alters the wage floor. If the minimum wage is increased, low-income workers earn more gross income, but this does not directly involve benefit withdrawal. It could potentially help escape the trap, not cause it.
- Option B: Benefits payments that are means-tested are explicitly reduced as income rises. This is the core mechanism of the poverty trap. If an individual's income increases, their means-tested benefits are cut, possibly by a large amount, leaving net income little changed. This can trap them in low net income despite higher gross income.
- Option C: Increasing subsidised housing payments for low-income earners means they receive more housing support. This increases their net income, making it easier to escape the trap, not cause it.
- Option D: Increasing the income level at which income tax is first paid (the personal allowance) means individuals pay less tax on their earnings. This increases net income, reducing the disincentive effect and helping to avoid the trap.
Therefore, only option B could result in an individual being caught in the poverty trap.
Key Takeaways
- The poverty trap is caused by the withdrawal of means-tested benefits and/or increases in taxes as income rises.
- Means-tested benefits are the key factor; universal benefits do not cause the trap.
- Policies that increase net income (higher tax thresholds, increased benefits) help alleviate the trap, while policies that reduce net income as gross income rises (benefit withdrawal) cause it.
Common Mistakes
- Confusing the poverty trap with low income in general. The trap is specifically about the disincentive effect of benefit withdrawal.
- Thinking that any increase in benefits causes the trap. Actually, increasing benefits can help escape the trap; it is the withdrawal of benefits that causes it.
- Assuming that a higher minimum wage causes the trap. It does not directly involve benefit withdrawal.
Things to Be Careful About
- Distinguish between means-tested and universal benefits. Only means-tested benefits are withdrawn as income rises.
- The poverty trap is about the marginal effective tax rate: the combined effect of benefit withdrawal and taxes on additional earnings.
- In this question, option B is the only one that describes a policy that reduces net income as gross income rises.
The diagram shows the impact on the labour market of the introduction of a national minimum wage (MW).
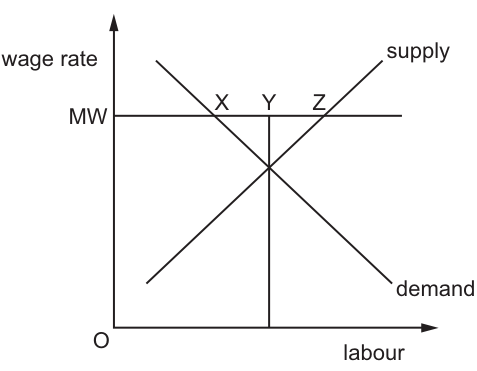
What do the distances XY and YZ represent?
Options
| XY | YZ | |
|---|---|---|
| A | increase in employed workers | existing workers made redundant |
| B | existing workers made redundant | unemployed new entrants |
| C | existing workers made redundant | increase in employed workers |
| D | unemployed new entrants | existing workers made redundant |
Working
The national minimum wage (MW) is set above the equilibrium wage, making it binding. At the MW:
- The quantity of labour demanded falls to the level at point X (where MW intersects the demand curve). Employment therefore falls from the original equilibrium level Y to X. The distance XY represents existing workers made redundant.
- The quantity of labour supplied rises to the level at point Z (where MW intersects the supply curve). The distance YZ represents the excess supply of labour — unemployed new entrants attracted by the higher wage but unable to find work because employment is determined by the lower quantity demanded at X.
Answer
B
B
Background Concept
In a competitive labour market, the equilibrium wage and employment are determined where the demand for labour (derived from the marginal revenue product of labour) equals the supply of labour. A national minimum wage is a legal price floor. If set above the equilibrium wage, it is binding and prevents the market from clearing. At the higher wage, firms demand less labour (movement up along the demand curve) while more workers are willing to supply their labour (movement up along the supply curve). The result is a fall in employment and the creation of unemployment equal to the excess of supply over demand.
Understanding the Question
The question presents a labour market diagram with a binding minimum wage (MW) drawn as a horizontal line above the equilibrium wage. Point X is where MW meets the demand curve, point Y is at the original equilibrium quantity (on the vertical line from the equilibrium intersection), and point Z is where MW meets the supply curve. The question asks what the horizontal distances XY and YZ represent.
Approach
Identify the original equilibrium employment level (OY). At the minimum wage, employment is determined by the quantity of labour demanded at point X (OX). The difference XY is therefore the reduction in employment. The quantity of labour supplied at the minimum wage is OZ. The difference YZ is the excess supply of labour — those who want jobs at the minimum wage but cannot be employed because firms only demand OX.
Step-by-Step Reasoning
- The equilibrium wage is below MW, so the minimum wage is binding.
- At the higher wage MW, firms move up along their demand curve for labour to point X. The quantity of labour demanded falls from OY to OX.
- Because employment in a competitive labour market with a minimum wage is determined by the demand side (firms will not hire more labour than they demand), employment falls to OX.
- The distance XY (OY minus OX) is therefore the number of workers who lose their jobs — existing workers made redundant.
- At the same time, workers move up along the supply curve to point Z. The quantity of labour supplied rises from OY to OZ.
- The distance YZ (OZ minus OY) represents the additional workers who enter the labour market or seek work because of the higher wage but cannot find jobs. These are unemployed new entrants.
- Option B correctly identifies XY as existing workers made redundant and YZ as unemployed new entrants.
Key Takeaways
- A binding minimum wage reduces employment and creates unemployment.
- Employment is determined by the demand curve at the minimum wage.
- The fall in employment (XY) affects existing workers; the excess supply (YZ) includes both displaced workers and new entrants to the labour market.
Common Mistakes
- Reversing XY and YZ, or confusing which group each distance represents.
- Assuming employment increases or that the supply curve determines employment at a minimum wage.
- Failing to recognise that the minimum wage is binding because it is drawn above equilibrium.
Things to Be Careful About
- Confirm that MW is above the equilibrium wage (binding); if it were below, it would have no effect.
- XY measures the change in employment (demand side), while YZ measures the resulting unemployment gap (supply minus demand at the minimum wage).
- The question asks for the specific interpretation of the distances, not just a general description of minimum wage effects.
What is an example of 'nudge' theory as applied to the prevention of tax evasion?
Options
A employing an extensive administration to ensure detection of evasion
B imposing heavy penalties on those who do evade tax
C providing information to taxpayers about the undesirable effects of tax evasion
D requiring employers to inform the tax authorities of workers' pay
Nudge theory involves altering the choice architecture to encourage desired behaviour without removing freedom of choice or using heavy penalties. Providing information to taxpayers about the undesirable effects of tax evasion is an example of a nudge because it aims to change taxpayers' perceptions and encourage voluntary compliance, rather than relying on detection or penalties.
Answer
C
C
Background Concept
Nudge theory, developed by Thaler and Sunstein, is a behavioural economics approach that uses subtle changes in the way choices are presented to influence people's decisions. It is based on the idea that individuals often do not act rationally due to cognitive biases, and that policymakers can 'nudge' them towards better outcomes without coercion or significant economic incentives. Nudges preserve freedom of choice and are typically low-cost. Examples include default options, framing, and social norms. In the context of tax evasion, a nudge would aim to increase voluntary compliance by altering the decision-making environment, rather than through detection, penalties, or mandates.
Understanding the Question
The question asks for an example of 'nudge' theory applied to preventing tax evasion. It presents four options, each representing a different policy approach. The task is to identify which one aligns with the principles of nudge theory: a policy that influences behaviour through subtle changes in information or choice presentation, without heavy enforcement or penalties.
Approach
To answer this, recall the core features of a nudge: it must be easy to avoid, not involve significant incentives or disincentives, and work by changing the 'choice architecture'. Evaluate each option against these criteria. Option A involves extensive administration to detect evasion – this is traditional enforcement. Option B imposes heavy penalties – this is a disincentive, not a nudge. Option D requires employers to report workers' pay – this is a mandate, removing choice. Option C provides information about the undesirable effects of tax evasion – this is a nudge because it aims to change behaviour by making the consequences more salient, without coercion.
Step-by-Step Reasoning
- Option A: Employing an extensive administration to ensure detection of evasion. This is a traditional enforcement approach, relying on the threat of being caught. It does not alter the choice architecture; it increases the probability of detection. This is not a nudge.
- Option B: Imposing heavy penalties on those who do evade tax. This uses a strong disincentive (punishment) to deter evasion. Nudges do not rely on significant penalties; they work through subtle influences. This is not a nudge.
- Option C: Providing information to taxpayers about the undesirable effects of tax evasion. This is a nudge because it makes the negative consequences of evasion more salient, potentially influencing taxpayers' decisions without removing their freedom to evade. It uses framing or social norms (e.g., 'most people pay their taxes') to encourage compliance. This fits the definition of a nudge.
- Option D: Requiring employers to inform the tax authorities of workers' pay. This is a mandatory reporting requirement, which removes the taxpayer's choice to report income accurately. It is a form of regulation, not a nudge.
Therefore, the correct answer is C.
Key Takeaways
- Nudge theory is a behavioural economics tool that influences behaviour through subtle changes in choice architecture, not through penalties, mandates, or heavy enforcement.
- In tax policy, nudges can include information campaigns, social norm messages, or simplifying the tax filing process.
- Distinguishing nudges from traditional policy tools is important for understanding modern approaches to market failure and government intervention.
Common Mistakes
- Confusing a nudge with any information campaign. Not all information provision is a nudge; it must be designed to alter the choice architecture in a way that leverages cognitive biases. However, in this question, providing information about undesirable effects is the best example among the options.
- Thinking that penalties or detection are examples of nudges because they also aim to change behaviour. Nudges are distinct because they do not rely on significant incentives or coercion.
- Overlooking that option D is a mandate, which removes choice, whereas nudges preserve freedom of choice.
Things to Be Careful About
- Nudge theory is part of behavioural economics and is often contrasted with traditional 'command-and-control' regulation. In multiple-choice questions, look for the option that involves a subtle change in the decision environment rather than a direct incentive or rule.
- The question specifically asks for an example of nudge theory as applied to tax evasion. Ensure the chosen option aligns with the definition of a nudge: easy to avoid, no heavy penalties, and works through psychological mechanisms.
The diagrams show the demand for and supply of labour.
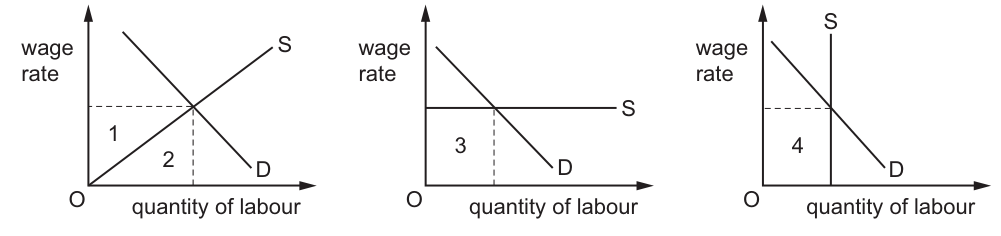
Which two areas represent economic rent?
Options
A 1 and 3
B 1 and 4
C 2 and 3
D 2 and 4
Economic rent is the payment to a factor of production in excess of its transfer earnings, represented by the area above the supply curve and below the wage rate.
- In Diagram 1, the supply curve slopes upward. Area 1 lies above the supply curve and below the equilibrium wage, so it represents economic rent. Area 2 lies below the supply curve and represents transfer earnings.
- In Diagram 2, the supply curve is perfectly elastic (horizontal) at the equilibrium wage. There is no area above the supply curve, so there is no economic rent. Area 3 represents transfer earnings.
- In Diagram 3, the supply curve is perfectly inelastic (vertical). The quantity of labour is fixed and cannot be transferred to alternative uses, so transfer earnings are zero. The entire wage payment (Area 4) therefore represents economic rent.
Therefore, the areas representing economic rent are 1 and 4.
B
Background Concept
Economic rent is the surplus payment made to a factor of production above what is necessary to keep it in its current use. This necessary payment is called transfer earnings, which represents the opportunity cost of the factor—the earnings it could obtain in its next best alternative employment. Graphically, in a labour market diagram with the wage rate on the vertical axis and quantity of labour on the horizontal axis, the supply curve represents the transfer earnings of workers. Economic rent is therefore the area above the supply curve and below the actual wage rate. The size of economic rent depends on the elasticity of supply: the more inelastic the supply, the greater the proportion of the total wage bill that constitutes economic rent.
Understanding the Question
The question presents three labour market diagrams with different supply curve shapes and asks which shaded areas represent economic rent. The command word is implicit (identify/select), and the task is to apply the definition of economic rent to each diagram. The key is to remember that economic rent is the area strictly above the supply curve. Diagram 1 has an upward-sloping supply, Diagram 2 has a perfectly elastic (horizontal) supply, and Diagram 3 has a perfectly inelastic (vertical) supply.
Approach
To solve this, evaluate each numbered area against the definition of economic rent:
- Locate the supply curve in each diagram.
- Identify whether the area lies above or below the supply curve.
- For the vertical supply case, consider the special implication: a perfectly inelastic supply means the factor is fixed and immobile, implying zero transfer earnings and therefore all income is economic rent.
- Select the option that correctly identifies the two areas representing rent.
Step-by-Step Reasoning
Diagram 1 (Upward-sloping supply):
The supply curve slopes upward from the origin, indicating that as wages rise, more workers are willing to supply their labour. Area 1 is the triangular region bounded by the wage rate (top), the supply curve (bottom-left), and the equilibrium quantity (right). This area lies entirely above the supply curve. Since the supply curve represents the minimum workers would accept (transfer earnings), any payment above this is economic rent. Thus, Area 1 is economic rent. Area 2 lies below the supply curve and represents the transfer earnings paid to workers to induce them to supply that quantity of labour.
Diagram 2 (Perfectly elastic supply):
The supply curve is horizontal at the equilibrium wage rate. This indicates that workers are willing to supply any quantity of labour at this specific wage, but none at a lower wage. Because the supply curve coincides with the wage rate, there is no vertical distance between the wage and the supply curve. Consequently, there is no area above the supply curve, meaning there is no economic rent. Area 3 lies below the supply curve and represents the total transfer earnings. Workers in this market earn exactly their transfer earnings and no more.
Diagram 3 (Perfectly inelastic supply):
The supply curve is vertical at a fixed quantity of labour. This represents a situation where the quantity of labour supplied does not change regardless of the wage rate—for example, a fixed number of workers with unique skills or a fixed amount of land. Because the quantity is fixed and cannot be transferred to alternative uses, the transfer earnings are zero. The entire wage bill paid to these workers is therefore economic rent. Area 4 is the rectangular area below the equilibrium wage and above the horizontal axis, representing the total wage bill. Since transfer earnings are zero, this entire area is economic rent.
Conclusion: Area 1 (from Diagram 1) and Area 4 (from Diagram 3) represent economic rent. The correct option is B.
Key Takeaways
- Economic rent is the area above the labour supply curve and below the wage rate.
- Transfer earnings are the area below the supply curve.
- With perfectly inelastic supply (vertical supply curve), transfer earnings are zero, so the entire wage payment is economic rent.
- With perfectly elastic supply (horizontal supply curve), there is no economic rent because the wage equals the supply price.
Common Mistakes
- Confusing Area 2 or Area 3 with economic rent: these areas lie below the supply curve and represent transfer earnings, not rent.
- Assuming Area 3 is economic rent because it is a rectangle: the shape is irrelevant; what matters is its position relative to the supply curve.
- Forgetting that a vertical supply curve implies zero transfer earnings, leading to the incorrect conclusion that only Area 1 is rent.
Things to Be Careful About
- Always identify the supply curve first. In Diagram 2, the supply curve is the horizontal line at the wage level, not the horizontal axis.
- In Diagram 3, do not confuse the vertical supply curve with the vertical axis. The supply curve is the vertical line at the fixed quantity. The area between the wage and this supply curve is not a standard rectangle, but the economic interpretation is that the entire payment is rent because the factor has no alternative use.
- Ensure you select exactly two areas as the question asks for "Which two areas".
In an economy with no government sector or foreign trade, the marginal propensity to consume is 0.6.
If the equilibrium level of national income is $10 000 million and the full employment level of national income is $15 000 million, by how much would investment have to increase to achieve full employment?
Options
A $1666 million
B $2000 million
C $3012 million
D $5000 million
Working
Multiplier = 1/(1 - MPC) = 1/(1 - 0.6) = 1/0.4 = 2.5
Output gap = $15,000 - $10,000 = $5,000 million
Required increase in investment = Output gap / Multiplier = $5,000 / 2.5 = $2,000 million
Answer
B
B
Background Concept
This question tests the Keynesian multiplier model in a closed economy without government. The multiplier measures the extent to which a change in an injection (e.g., investment, government spending, or exports) causes a larger change in national income. The formula for the multiplier in a simple closed economy with no government is:
Multiplier = 1 / (1 - MPC)
where MPC is the marginal propensity to consume. The output gap is the difference between the full employment level of national income (Yf) and the current equilibrium level (Ye). To close the gap and achieve full employment, the injection must increase by the gap divided by the multiplier.
Understanding the Question
The economy is closed (no exports/imports, no government sector). The marginal propensity to consume (MPC) is 0.6. The equilibrium national income is $10,000 million, and the full employment level is $15,000 million. The question asks: by how much must investment (I) increase to raise national income from the equilibrium to the full employment level?
This is a standard application of the multiplier: the change in income equals the multiplier times the change in investment. We need to find ΔI such that ΔY = multiplier * ΔI = gap.
Approach
- Compute the multiplier from the given MPC.
- Determine the output gap: Yf - Ye.
- Rearrange the multiplier formula: ΔI = ΔY / multiplier.
- Substitute the numbers and calculate.
Step-by-Step Reasoning
- MPC = 0.6. The marginal propensity to save (MPS) = 1 - MPC = 0.4. In a closed economy with no government, the multiplier is 1/MPS = 1/0.4 = 2.5. Alternatively, directly use 1/(1-MPC) = 1/0.4 = 2.5.
- Output gap = $15,000 million - $10,000 million = $5,000 million.
- The multiplier formula: ΔY = k * ΔI, where k is the multiplier. So ΔI = ΔY / k = $5,000 million / 2.5 = $2,000 million.
- Therefore, investment must increase by $2,000 million to achieve full employment.
Key Takeaways
- The multiplier is a key concept in macroeconomics: it shows how changes in autonomous spending have a multiplied effect on national income.
- In a closed economy without government, the multiplier is simply 1/(1-MPC) or 1/MPS.
- The output gap is the difference between full employment and equilibrium income; closing it requires a change in an injection equal to the gap divided by the multiplier.
Common Mistakes
- Confusing the output gap: some students might subtract the equilibrium from full employment incorrectly (e.g., $10,000 - $15,000 = -$5,000) but then use the absolute value; the sign is not important for the magnitude but the direction is an increase in investment.
- Using the wrong multiplier: if the economy had a government or foreign sector, the multiplier would be smaller. Here it is a simple closed economy, so the formula is straightforward.
- Forgetting to divide by the multiplier: some might multiply the gap by the multiplier, giving $5,000 * 2.5 = $12,500, which is not an option but would be a common error.
- Misreading the values: the figures are in millions of dollars, so the answer is $2000 million, not $2 or $2,000,000 (though it is equivalent).
Things to Be Careful About
- Always correctly identify the economic model: closed vs open, with or without government. The multiplier formula changes.
- Ensure the units are consistent: here both incomes are in millions, so the answer is in millions.
- The question asks for the increase in investment (ΔI), not the new level of investment. The answer is $2000 million.
- Check the answer options: $2000 million is option B.
What is a definition of hysteresis unemployment?
Options
A people who become temporarily unemployed because it takes a short period of time to find a job after they leave school
B people who become unemployed when there is a recession but who will find employment as the economy comes out of recession
C people who become unemployed for a long period of time due to a loss of job skills and work experience while unemployed
D people who become unemployed when established firms close and new firms are created as technology advances
Answer
Hysteresis unemployment occurs when a period of high unemployment causes a permanent increase in the natural rate of unemployment. Workers who are unemployed for a long time lose their job skills, work experience, and attachment to the labour force, making it harder for them to find work even after the economy recovers. This is described in option C.
C
Background Concept
Hysteresis is a concept borrowed from physics, meaning that the effect of a cause persists even after the cause is removed. In labour economics, hysteresis unemployment refers to a situation where a temporary economic shock (such as a deep recession) permanently raises the natural rate of unemployment. The key mechanism is that long-term unemployment erodes workers' human capital — their skills, work habits, and networks — and may also reduce employers' willingness to hire them. This means that even when aggregate demand recovers and the original reason for the job loss is gone, these workers remain unemployed. The natural rate of unemployment (the rate consistent with stable inflation) thus becomes path-dependent: it depends on the economy's history, not just its current conditions.
Understanding the Question
This is a straightforward multiple-choice question asking for the correct definition of hysteresis unemployment. The four options describe different types of unemployment:
- A describes frictional unemployment (short-term, transitional).
- B describes cyclical or demand-deficient unemployment (tied to the business cycle, expected to reverse).
- C describes the core hysteresis mechanism: long-term unemployment leading to skill loss and reduced employability.
- D describes structural unemployment (mismatch between workers' skills and the jobs available due to technological change).
The question tests whether you can distinguish hysteresis from other, more familiar, categories of unemployment.
Approach
Read each option carefully and identify the key feature that distinguishes hysteresis: the idea that unemployment persists even after the original cause (e.g., a recession) has ended, because of damage to the workers' own employability. Option C is the only one that mentions a loss of job skills and work experience while unemployed — this is the hallmark of hysteresis. The other options describe unemployment that is either temporary by nature (A, B) or caused by a permanent structural shift in the economy (D).
Step-by-Step Reasoning
-
Option A describes frictional unemployment: people moving between jobs or entering the labour force for the first time. This is short-term and not associated with permanent damage to workers' skills. Eliminate.
-
Option B describes cyclical unemployment: workers laid off during a recession who are expected to be rehired when the economy recovers. This is temporary and tied to the business cycle. Eliminate.
-
Option C describes exactly the hysteresis mechanism: long-term unemployment leads to a loss of job skills and work experience, making it harder for these workers to find jobs even after the economy improves. This is the correct definition.
-
Option D describes structural unemployment: a mismatch between the skills workers have and the skills demanded by new industries. While this can also be long-term, the cause is a permanent change in the structure of the economy (e.g., automation), not the loss of skills due to unemployment itself. Hysteresis is specifically about the self-reinforcing effect of unemployment on employability.
Therefore, the correct answer is C.
Key Takeaways
- Hysteresis unemployment is a type of long-term unemployment that persists because the experience of being unemployed damages workers' human capital.
- It is distinct from cyclical unemployment (which reverses with recovery) and structural unemployment (which is caused by a permanent shift in demand for skills).
- The concept is important for policy: it implies that allowing unemployment to remain high for a prolonged period can permanently reduce the economy's potential output and raise the natural rate of unemployment.
Common Mistakes
- Confusing hysteresis with structural unemployment. Both can be long-term, but the cause differs: structural unemployment arises from a mismatch between skills and available jobs (e.g., coal miners in a renewable energy economy), while hysteresis arises from the process of being unemployed itself eroding skills.
- Choosing option B because it mentions a recession and recovery. Hysteresis is precisely about the failure to recover fully after a recession.
- Choosing option A because it mentions 'temporarily' — hysteresis is the opposite of temporary.
Things to Be Careful About
- Read the wording of each option carefully. Option C explicitly states 'loss of job skills and work experience while unemployed' — this is the key phrase that signals hysteresis.
- Remember that hysteresis is not just any long-term unemployment; it is specifically unemployment that becomes self-perpetuating.
An economy has a positive output gap.
What is happening to economic growth and the general price level?
Options
| economic growth | general price level | |
|---|---|---|
| A | above trend growth rate | falling |
| B | above trend growth rate | rising |
| C | below trend growth rate | falling |
| D | below trend growth rate | rising |
Answer
A positive output gap means actual GDP exceeds potential GDP. This occurs when the economy is growing above its trend rate. The excess demand in the economy puts upward pressure on the general price level, causing inflation. Therefore, economic growth is above the trend growth rate and the general price level is rising.
Answer
B
B
Background Concept
An output gap is the difference between actual GDP and potential GDP. Potential GDP is the maximum sustainable level of output an economy can produce when all resources are fully employed. A positive output gap (also called an inflationary gap) occurs when actual GDP exceeds potential GDP. This typically happens during the boom phase of the business cycle, when demand is very strong. The excess demand bids up prices, leading to demand-pull inflation. Growth is above the long-run trend rate.
Understanding the Question
The question presents a single fact: "An economy has a positive output gap." It then asks what is happening to two variables: economic growth (relative to the trend growth rate) and the general price level (rising or falling). The answer requires knowing the standard macroeconomic relationship between the output gap, the phase of the business cycle, and inflation.
Approach
- Recall the definition of a positive output gap.
- Identify the phase of the business cycle associated with a positive output gap (boom).
- Determine the growth rate relative to trend during a boom (above trend).
- Determine the direction of the general price level during a boom (rising, due to demand-pull inflation).
- Match these two conclusions to the correct row in the table.
Step-by-Step Reasoning
- Positive output gap: Actual GDP > Potential GDP.
- Economic growth: During a boom, the economy is expanding rapidly. The actual growth rate is above the long-run trend growth rate. So "above trend growth rate" is correct.
- General price level: With actual output above potential, there is excess demand in the economy. This excess demand pulls up prices – demand-pull inflation. Therefore, the general price level is rising.
- Matching to options:
- A: above trend growth, falling prices – incorrect (prices rise, not fall).
- B: above trend growth, rising prices – correct.
- C: below trend growth, falling prices – incorrect (growth is above trend, not below).
- D: below trend growth, rising prices – incorrect (growth is above trend).
Thus, the correct answer is B.
Key Takeaways
- A positive output gap signals an overheating economy with above-trend growth and rising inflation.
- A negative output gap (recessionary gap) signals below-trend growth and falling or low inflation.
- The output gap is a key indicator of the business cycle phase and helps predict policy responses.
Common Mistakes
- Confusing a positive output gap with a recession (negative output gap).
- Thinking that a positive output gap means growth is below trend (it is above).
- Assuming that a positive output gap always leads to falling prices (it leads to rising prices due to excess demand).
Things to Be Careful About
- The question asks about the general price level, not the rate of inflation. A rising price level means positive inflation.
- The term "above trend growth rate" refers to the actual growth rate being higher than the long-run average, not to the level of output being above potential (though they are related).
What is a factor affecting the occupational mobility of labour?
Options
A education and training
B immigration controls
C price of housing
D transport infrastructure
Reasoning
Occupational mobility of labour refers to the ability and willingness of workers to move between different jobs or occupations. The most direct factor influencing this is education and training, as it determines the skills a worker possesses and therefore the range of jobs they can perform. Immigrants, housing prices, and transport infrastructure mainly affect geographical mobility (willingness to move between regions) rather than occupational mobility.
Answer
A
A
Background Concept
Labour mobility is the ease with which workers can change jobs. It is divided into:
- Occupational mobility: moving between different types of jobs (e.g., from nursing to teaching).
- Geographical mobility: moving between different locations (e.g., from rural to urban areas).
Occupational mobility depends heavily on transferable skills, qualifications, retraining opportunities, and personal attitudes. Education and training directly expand the set of occupations a worker can enter.
Understanding the Question
This is a multiple-choice question asking for a factor specifically affecting occupational mobility. Three of the options (immigration controls, housing prices, transport infrastructure) primarily influence where a worker is willing to live rather than what job they can do.
Approach
Identify the option that relates to the skill or qualification requirements of jobs. The other options relate to moving location rather than changing occupation.
Step-by-Step Reasoning
-
Option A (education and training): Correct. Without appropriate education or training, a worker cannot enter many occupations (e.g., a doctor needs medical training; a plumber needs an apprenticeship). Education directly affects occupational mobility.
-
Option B (immigration controls): Mainly affects the movement of workers between countries (geographical mobility) rather than the ability to switch occupations within a country.
-
Option C (price of housing): Affects the affordability of living in an area (geographical mobility). A worker might be unable to move to a city with jobs because of high rents, but this does not stop them changing occupation within their current location.
-
Option D (transport infrastructure): Affects commuting and relocation ease (geographical mobility). Better transport may allow a worker to reach more distant employment, but does not change the types of jobs they can do.
Key Takeaways
- Occupational mobility = ability to change job type; geographical mobility = ability to change location.
- Education and training are the key enablers of occupational mobility.
- The other factors listed primarily affect geographical mobility.
Common Mistakes
- Confusing occupational and geographical mobility. Many students incorrectly select factors that affect willingness to move (housing, transport) instead of ability to perform different jobs.
- Believing immigration controls only affect incoming foreign workers but forgetting they also prevent some workers from moving occupationally within a country (this is a minor misinterpretation; immigration controls primarily affect cross-border movement, not internal occupational change).
Things to Be Careful About
- The question specifically asks about occupational mobility, so answer the exact aspect of mobility tested.
- Do not overthink: the most direct and obvious factor is education and training.
A country's government decides to set artificially low interest rates.
What describes a negative consequence to this country of this policy?
Options
A a higher rate of consumer price inflation
B a rapid growth in gross domestic product
C an increase in investment by manufacturers and real estate developers
D a reduction in borrowing by consumers
Reasoning
Artificially low interest rates reduce the cost of borrowing, stimulating consumption and investment. This increases aggregate demand. If the economy is at or near full employment, the increase in AD causes demand-pull inflation, which is a negative consequence.
Answer
A
A
Background Concept
Central banks set interest rates to influence the level of economic activity. Lower interest rates reduce the cost of borrowing for consumers and firms, making loans for mortgages, cars, and business investment cheaper. They also reduce the return on savings, discouraging saving and encouraging spending. This increase in consumption and investment shifts the aggregate demand (AD) curve to the right. If the economy has spare capacity, the increase in AD leads to higher real output without much inflation. However, if the economy is already at or near full capacity, the increase in AD primarily pushes up the price level, creating demand-pull inflation. High inflation erodes purchasing power, creates uncertainty, and can harm long-term economic stability, making it a negative consequence.
Understanding the Question
The question states that a government decides to set artificially low interest rates. This means the central bank (or government) is keeping interest rates below the market-clearing level, likely to stimulate the economy. The question asks: "What describes a negative consequence to this country of this policy?" Among the options, we need to identify which one is a negative outcome. Options B and C (rapid GDP growth, increase in investment) are typically viewed as positive outcomes, while option D (reduction in borrowing) is false because low rates encourage borrowing. Option A (higher consumer price inflation) is a negative consequence because it reduces the real value of money and can lead to economic instability.
Approach
- Understand the effect of low interest rates on aggregate demand.
- Trace the chain of causation: lower interest rates -> higher consumption and investment -> higher AD -> if economy is at full capacity, higher price level (inflation).
- Evaluate each option: A is a negative consequence; B and C are positive; D is incorrect direction.
- Conclude that A is the correct answer.
Step-by-Step Reasoning
- Step 1: Low interest rates reduce the cost of borrowing. When interest rates are low, monthly payments on loans are smaller, so consumers are more willing to borrow for big-ticket items like houses and cars. Firms are more willing to borrow to invest in new machinery or factories.
- Step 2: This increases consumption and investment. Both are components of aggregate demand (AD = C + I + G + X-M). So AD rises.
- Step 3: The effect on output and prices depends on the state of the economy. If there is spare capacity (unemployed resources), the increase in AD raises real GDP without much price increase. But if the economy is near full employment, the increase in AD mainly pushes up prices, causing demand-pull inflation.
- Step 4: Inflation is a negative consequence. High inflation erodes the purchasing power of money, can lead to uncertainty, reduce international competitiveness, and may require painful corrective policies later. It is therefore a negative outcome.
- Step 5: Evaluate other options.
- B & C: Rapid GDP growth and increased investment are generally desirable (positive) outcomes, not negative. The question asks for a negative consequence, so these are not correct.
- D: Low interest rates encourage borrowing, not reduce it. So this is factually incorrect.
Thus, only option A describes a negative consequence.
Key Takeaways
- Expansionary monetary policy (low interest rates) can stimulate growth but also risks causing inflation when the economy is at full capacity.
- The trade-off between growth and inflation is a central macroeconomic policy conflict.
- When answering multiple-choice questions, read carefully: the question asks for a "negative consequence", so positive outcomes should be eliminated.
Common Mistakes
- Choosing B or C because students think rapid growth or investment might be negative in some contexts (e.g., overheating). However, the question does not indicate that growth is excessive; it asks for a direct negative consequence of the policy. The most direct negative consequence is inflation.
- Confusing the direction of borrowing: low rates reduce borrowing (D) is the opposite of what actually happens.
- Overthinking: the simplest answer is often correct; inflation is the classic negative side-effect of low interest rates.
Things to Be Careful About
- Always align the answer with the question's specific wording: "negative consequence".
- Understand the transmission mechanism of monetary policy: the chain from interest rates to AD to inflation.
- Distinguish between positive and negative outcomes: GDP growth is generally positive, while inflation is generally negative when it is high or unexpected.
- In an exam, eliminate obviously wrong options first (D is factually opposite), then choose the best remaining.
According to the quantity theory of money, which combination would result in the general level of prices remaining unchanged?
Options
| money supply | total number of transactions | velocity of circulation | |
|---|---|---|---|
| A | remains unchanged | remains unchanged | rises by 3% |
| B | rises by 3% | remains unchanged | rises by 3% |
| C | rises by 3% | rises by 3% | remains unchanged |
| D | rises by 3% | rises by 3% | rises by 3% |
Reasoning
The quantity theory of money states MV = PT, where M is money supply, V is velocity of circulation, P is price level, and T is total number of transactions. For P to remain unchanged, the percentage change in MV must equal the percentage change in T.
- Option A: M unchanged, V rises 3% -> MV rises 3%, T unchanged -> P rises 3%.
- Option B: M rises 3%, V rises 3% -> MV rises 6%, T unchanged -> P rises 6%.
- Option C: M rises 3%, V unchanged -> MV rises 3%, T rises 3% -> P unchanged.
- Option D: M rises 3%, V rises 3% -> MV rises 6%, T rises 3% -> P rises 3%.
Only option C results in P unchanged.
Answer
C
C
Background Concept
The quantity theory of money is expressed by the equation of exchange: MV = PT. Here:
- M = money supply
- V = velocity of circulation (the average number of times a unit of money is used in transactions)
- P = general price level
- T = total number of transactions (real output in some formulations)
The equation is an identity that always holds. In its simplest form, it suggests that changes in the money supply (M) directly affect the price level (P), assuming V and T are constant. However, V and T can also change. The question asks for the combination of changes in M, V, and T that leaves P unchanged.
Understanding the Question
The question presents four options, each specifying a percentage change in money supply, total number of transactions, and velocity of circulation. We need to determine which combination results in no change in the general price level. This requires applying the equation MV = PT and understanding that if the product MV changes by the same percentage as T, then P remains constant.
Approach
- Write the equation: MV = PT.
- For P to remain unchanged, the percentage change in MV must equal the percentage change in T.
- Since percentage changes add when multiplying, %Δ(MV) = %ΔM + %ΔV.
- Condition: %ΔM + %ΔV = %ΔT.
- Check each option against this condition.
Step-by-Step Reasoning
- Option A: %ΔM = 0%, %ΔV = +3%, %ΔT = 0%. Then %ΔM + %ΔV = 3%, which is not equal to %ΔT (0%). So P would rise by 3%.
- Option B: %ΔM = +3%, %ΔV = +3%, %ΔT = 0%. Sum = 6%, not equal to 0%. P rises by 6%.
- Option C: %ΔM = +3%, %ΔV = 0%, %ΔT = +3%. Sum = 3%, equal to %ΔT = 3%. Therefore P unchanged.
- Option D: %ΔM = +3%, %ΔV = +3%, %ΔT = +3%. Sum = 6%, not equal to 3%. P rises by 3%.
Thus only option C satisfies the condition.
Key Takeaways
- The quantity theory equation is a useful framework for understanding the relationship between money, prices, and transactions.
- Changes in money supply do not automatically change prices if offset by changes in velocity or real transactions.
- The condition for constant price level is that the percentage change in the product MV equals the percentage change in T.
Common Mistakes
- Assuming that only money supply matters and ignoring changes in velocity or transactions.
- Forgetting that percentage changes add when variables are multiplied.
- Misinterpreting T as real output instead of total transactions (though in many contexts they are equivalent).
Things to Be Careful About
- The equation is an identity; it holds ex post. The question assumes the relationship holds for the given changes.
- Ensure that the percentage changes are applied correctly: a 3% rise means multiply by 1.03.
- The question uses "total number of transactions" which is T; do not confuse with real GDP.
- In the quantity theory, velocity is often assumed stable in the short run, but here it changes in some options.
A government increases its inflation rate target from 3% to 5%.
What is a likely reason for this?
Options
A to increase economic sustainability
B to increase saving
C to reduce a balance of payments deficit
D to reduce unemployment
Reasoning
A higher inflation target can reduce unemployment in the short run if the economy is operating below full employment, as predicted by the traditional Phillips curve. Option A (increase economic sustainability) is unlikely because higher inflation typically reduces sustainability. Option B (increase saving) is incorrect because higher inflation reduces the real return on saving. Option C (reduce a balance of payments deficit) is wrong because higher inflation makes exports less competitive. Option D (reduce unemployment) is the correct reason: a higher inflation target may allow expansionary monetary policy to lower unemployment.
Answer
D
D
Background Concept
The Phillips curve shows an inverse relationship between inflation and unemployment in the short run. When inflation is higher, firms may raise nominal wages and prices, leading to increased output and lower unemployment temporarily. This trade-off is a central concept in macroeconomic policy. A government may choose a higher inflation target if it prioritises reducing unemployment, accepting higher inflation as a cost.
Understanding the Question
The question asks for a likely reason a government would increase its inflation rate target from 3% to 5%. The four options represent possible macroeconomic objectives. The correct reason must be the one that is consistent with economic theory: a higher inflation target is typically associated with attempts to stimulate the economy and reduce unemployment, especially when the economy is in a recession or has high unemployment.
Approach
First, recall the Phillips curve trade-off. Second, evaluate each option against this trade-off. Option D directly matches the trade-off. Options A, B, and C are inconsistent because higher inflation tends to reduce sustainability (greater volatility), discourage saving (real returns fall), and worsen the balance of payments (exports become less competitive). Thus, D is the only plausible reason.
Step-by-Step Reasoning
- The Phillips curve (traditional) suggests that in the short run, there is an inverse relationship between inflation and unemployment. That is, lower unemployment comes at the cost of higher inflation, and vice versa.
- If the government increases the inflation target, it signals willingness to accept higher inflation. This could allow expansionary monetary policy (e.g., lower interest rates) to boost aggregate demand, reducing unemployment.
- Option A: economic sustainability. Sustainability (long-term growth without environmental or social damage) is not directly improved by higher inflation; in fact, high inflation can harm sustainable growth. So A is unlikely.
- Option B: increasing saving. Higher inflation erodes the real value of savings, so it discourages saving. Therefore B is wrong.
- Option C: reducing a balance of payments deficit. Higher inflation makes domestic goods more expensive relative to foreign goods, worsening the trade balance. So C is incorrect.
- Option D: reducing unemployment. As explained, the Phillips curve trade-off supports this. Even though in the long run the trade-off disappears (expectations adjust), in the short run a higher inflation target can reduce unemployment. This is a standard reason for a government to raise its inflation target.
Therefore, D is the correct answer.
Key Takeaways
The Phillips curve trade-off is a fundamental concept for understanding why governments might accept higher inflation to reduce unemployment. Short-run trade-offs are distinct from long-run neutrality. Always consider the effect on each macroeconomic objective when evaluating policy changes.
Common Mistakes
- Confusing the short-run Phillips curve with the long-run vertical Phillips curve: the question is about a likely reason, and the short-run trade-off is the standard explanation.
- Thinking higher inflation directly reduces the balance of payments deficit: it actually worsens it.
- Assuming higher inflation increases saving: it reduces real returns, so saving falls.
Things to Be Careful About
- The question asks for a "likely reason", not a certain outcome. The Phillips curve trade-off is a theoretical prediction, but in practice other factors matter.
- Distinguish between short-run and long-run effects: in the long run, higher inflation does not reduce unemployment, but the question is about a reason for the policy change, which is typically based on short-run benefits.
- Read each option carefully: sustainability is not directly linked to inflation target changes; it is more about stable growth.
What would be a macroeconomic policy objective for a government in a developed economy?
Options
A to improve sustainability
B to provide public goods
C to reduce the power of trade unions
D to subsidise the electricity supply industry
Answer
A macroeconomic policy objective is a goal that affects the whole economy, such as economic growth, low inflation, low unemployment, a stable balance of payments, or sustainability. Option A, 'to improve sustainability', is a recognised macroeconomic objective for a developed economy, as it concerns the long-term viability of economic activity and resource use. The other options are microeconomic policies or specific interventions: providing public goods (B) is a microeconomic role of government to correct market failure; reducing the power of trade unions (C) is a labour market policy; and subsidising the electricity supply industry (D) is a microeconomic industrial or energy policy. Therefore, only A is a macroeconomic policy objective.
A
Background Concept
Macroeconomic policy objectives are the broad goals that a government pursues to manage the performance of the national economy as a whole. The standard set of macroeconomic objectives includes:
- Economic growth: a sustained increase in the economy's output of goods and services.
- Low unemployment (or full employment): minimising the number of people who are willing and able to work but cannot find jobs.
- Low and stable inflation: typically a target of around 2% per year.
- A stable balance of payments: avoiding persistent deficits or surpluses on the current account.
- Sustainability: ensuring that current economic activity does not compromise the ability of future generations to meet their own needs. This includes environmental sustainability and the sustainable use of resources.
These are distinct from microeconomic policies, which target specific markets, industries, or groups of firms and consumers. Microeconomic policies include correcting market failures (e.g., providing public goods, regulating monopolies, subsidising specific industries) and intervening in particular markets (e.g., labour market policies affecting trade unions).
Understanding the Question
This is a multiple-choice question asking which of the four options is a macroeconomic policy objective for a government in a developed economy. The key is to recognise that a macroeconomic objective applies to the entire economy, not to a specific sector, industry, or market. The question tests the distinction between broad national-level goals and narrower, targeted interventions.
Approach
- Recall the standard list of macroeconomic objectives.
- Evaluate each option against that list.
- Eliminate options that are microeconomic policies or specific interventions.
- Select the option that matches a recognised macroeconomic objective.
Step-by-Step Reasoning
-
Option A: 'to improve sustainability' – Sustainability is a recognised macroeconomic objective, particularly in developed economies where environmental concerns and long-term resource management are high priorities. It is a goal for the whole economy, concerning how growth is achieved and whether it can be maintained without depleting resources or causing irreversible environmental damage. This is a valid macroeconomic objective.
-
Option B: 'to provide public goods' – Providing public goods (e.g., national defence, street lighting, lighthouses) is a microeconomic policy to correct a specific type of market failure. Public goods are non-excludable and non-rival, so the private market under-provides them. The government steps in to supply them directly. This is a microeconomic intervention, not a macroeconomic objective.
-
Option C: 'to reduce the power of trade unions' – This is a labour market policy aimed at changing the balance of power between employers and employees in a specific factor market. It is a microeconomic or structural policy, not a macroeconomic objective. While it might have macroeconomic consequences (e.g., on wage inflation or productivity), the objective itself is microeconomic.
-
Option D: 'to subsidise the electricity supply industry' – This is a microeconomic industrial policy or a sector-specific subsidy. It targets a particular industry (electricity supply) to achieve goals such as lower prices, energy security, or promoting renewable energy. It is not a macroeconomic objective.
Therefore, only Option A is a macroeconomic policy objective.
Key Takeaways
- Macroeconomic objectives are economy-wide goals: growth, low inflation, low unemployment, balance of payments stability, and sustainability.
- Microeconomic policies target specific markets, industries, or groups (e.g., public goods, trade unions, specific subsidies).
- The distinction is important for understanding the scope and nature of government intervention.
Common Mistakes
- Confusing a microeconomic policy (like providing public goods or subsidising an industry) with a macroeconomic objective. The question explicitly asks for a macroeconomic objective, so options that are specific interventions should be eliminated.
- Thinking that any government policy that affects the economy is automatically a macroeconomic objective. Many policies have macroeconomic effects but are not themselves objectives.
Things to Be Careful About
- Read the question carefully: it asks for a 'macroeconomic policy objective', not just any government policy.
- Remember that 'sustainability' is now a standard macroeconomic objective, especially in the context of developed economies and the 9708 syllabus.
- Do not overthink: the correct answer is the one that fits the standard list of macroeconomic objectives.
An economy is at its natural rate of unemployment.
Under which circumstances will an increase in government spending aimed at reducing unemployment be most likely to conflict with a government's objective of low inflation?
Options
A if inflationary expectations are unchanged
B if inflationary expectations fall
C if labour productivity increases
D if labour supply increases
Reasoning
The economy is at its natural rate of unemployment, so the actual unemployment rate equals the non-accelerating inflation rate of unemployment (NAIRU). Any attempt to reduce unemployment below the natural rate using expansionary fiscal policy will increase aggregate demand. According to the expectations-augmented Phillips curve, if inflationary expectations are unchanged, the short-run trade-off exists, but in the long run the economy returns to the natural rate with higher inflation. Therefore, an increase in government spending aimed at reducing unemployment will create a conflict with low inflation when inflationary expectations are unchanged (Option A). If inflationary expectations fall (B), the short-run Phillips curve shifts down, reducing the inflation cost. If labour productivity (C) or labour supply (D) increases, the natural rate itself may fall, allowing lower unemployment without inflation.
Answer
A
A
Background Concept
The natural rate of unemployment (also called the NAIRU – non-accelerating inflation rate of unemployment) is the rate of unemployment at which inflation is stable. The Phillips curve shows the relationship between unemployment and inflation. In the short run, there is a trade-off: lower unemployment can be achieved at the cost of higher inflation. However, in the long run, the Phillips curve is vertical at the natural rate because expectations adjust. The expectations-augmented Phillips curve incorporates the role of expected inflation: the short-run trade-off exists only when actual inflation differs from expected inflation.
Understanding the Question
The question states that the economy is at its natural rate of unemployment. The government increases spending to reduce unemployment (i.e., it tries to push unemployment below the natural rate). The question asks: under which condition will this policy most likely conflict with the objective of low inflation? We need to identify which of the four options makes the inflationary consequences most severe.
Approach
We use the Phillips curve framework. The key factor is the position of the short-run Phillips curve, which depends on inflationary expectations and supply-side factors. Compare how each option affects the trade-off.
Step-by-Step Reasoning
-
Option A: If inflationary expectations are unchanged. The short-run Phillips curve remains in its current position. An increase in aggregate demand moves the economy leftwards along the curve, reducing unemployment below the natural rate and raising inflation. In the long run, expectations adjust upwards, shifting the short-run curve up, and the economy returns to the natural rate with even higher inflation. This creates a clear conflict between lower unemployment and low inflation.
-
Option B: If inflationary expectations fall. The short-run Phillips curve shifts downwards. This means that for any given unemployment rate, inflation is lower. The expansionary policy would cause less inflation than in the unchanged expectations case. The conflict is reduced.
-
Option C: If labour productivity increases. The potential output of the economy rises. This can reduce the natural rate of unemployment (the economy can sustain lower unemployment without inflation). The increase in government spending may be absorbed by the increased productive capacity, so the inflationary pressure is limited. The conflict is less.
-
Option D: If labour supply increases. Similar to option C, an increase in labour supply shifts the long-run aggregate supply curve to the right, potentially lowering the natural rate. Again, the conflict is reduced.
Therefore, the situation where the conflict is most likely to occur is when inflationary expectations are unchanged, because the short-run trade-off is fully present and no offsetting supply-side improvements occur.
Key Takeaways
- The natural rate of unemployment is crucial for understanding the long-run limits of macroeconomic policy.
- The short-run Phillips curve is not fixed; it shifts with expectations and supply-side factors.
- Expansionary demand-side policy cannot permanently reduce unemployment below the natural rate; it only causes higher inflation in the long run.
- Conflicting objectives (low unemployment and low inflation) are most acute when the economy is at the natural rate and expectations are not adjusting favourably.
Common Mistakes
- Thinking that the Phillips curve trade-off always exists, regardless of the initial position of the economy.
- Confusing the short-run and long-run Phillips curve.
- Ignoring the role of inflationary expectations in shifting the curve.
- Assuming that an increase in labour productivity or labour supply does not affect the natural rate.
- Choosing option B or C because they seem to reduce inflation, but missing that the question asks for the circumstance that most likely conflicts with low inflation.
Things to Be Careful About
- The phrase "at its natural rate of unemployment" is key: it means the economy is at full employment in the sense of NAIRU, so any further reduction in unemployment will be unsustainable.
- The question is about "most likely to conflict", so we need the option that makes the inflation cost highest.
- Understand that the natural rate can change over time with supply-side factors.
- In an MCQ, evaluate each option systematically using the Phillips curve model.
An economy imports a large proportion of its raw materials. Its exchange rate depreciates.
What is the impact on the external and internal value of money?
Options
| external value of money | internal value of money | |
|---|---|---|
| A | rises | rises |
| B | rises | falls |
| C | falls | rises |
| D | falls | falls |
Answer
The external value of money is the exchange rate — the price of one currency in terms of another. A depreciation means the domestic currency buys fewer units of foreign currency, so the external value falls.
This economy imports a large proportion of its raw materials. When the domestic currency depreciates, imports become more expensive in domestic currency terms. The cost of imported raw materials rises, so production costs increase. These higher costs are passed on to consumers in the form of higher prices for finished goods. The general price level rises, meaning each unit of domestic currency buys fewer goods and services — its purchasing power, i.e. its internal value, falls.
Therefore, both values fall.
Answer
D
D
Background Concept
External value of money refers to the purchasing power of a currency in international markets — it is simply the exchange rate. For example, if GBP/USD falls from 1.30 to 1.20, one pound buys fewer US dollars, so its external value has fallen.
Internal value of money refers to the purchasing power of a currency within the domestic economy — what it can buy in terms of goods and services. When the general price level rises (inflation), the internal value falls because each unit of currency buys less. The internal value is effectively the reciprocal of the price level.
These two values are connected via the prices of traded goods. If an economy is a significant importer — especially of raw materials and intermediate goods that feed into domestic production — a change in the exchange rate feeds through directly into domestic costs and prices.
Understanding the Question
The question presents a factual scenario: an economy imports a large proportion of its raw materials. We are then told its exchange rate depreciates. We need to trace the combined impact on both the external and internal value of money and pick the option that correctly describes both outcomes.
The word "large proportion" is the key qualifier — it signals that the import channel is strong enough to transmit a depreciation into higher domestic prices.
Approach
- Define both terms and decide what effect a depreciation has on the external value (clear and unidirectional).
- Build the causal chain from depreciation to the domestic price level, using the fact that raw materials are imported.
- Combine the two conclusions to identify the correct row in the table.
Step-by-Step Reasoning
Step 1: External value. Depreciation means the domestic currency has weakened — it takes more units of domestic currency to buy one unit of foreign currency. Therefore, its external value unambiguously falls. This eliminates options A and B, both of which say the external value rises.
Step 2: Internal value. Now we need the effect on the price level. Key fact: imports a large proportion of raw materials. When the domestic currency depreciates, the domestic-currency price of each imported raw material rises.
Chain: depreciation -> imported raw materials cost more in domestic currency -> firms' input costs rise -> firms raise their output prices to maintain profit margins (or at least pass on the higher cost) -> the general price level rises -> each unit of domestic currency now buys fewer goods and services -> the internal value of money falls.
Both values fall. Option D says exactly that.
Step 3: Check remaining options. Option C says external falls but internal rises — that would require the price level to fall after a depreciation, which is the opposite direction. Option B is the reverse, won by a candidate who confuses a 'stronger' currency with a 'weaker' price level effect.
Key Takeaways
- The external value of money is the exchange rate; depreciation = fall.
- The internal value of money is purchasing power; inflation = fall.
- An import-dependent economy transmits exchange rate changes into domestic inflation through the cost channel (import prices -> costs -> consumer prices). The strength of this pass-through depends on the share of imports in consumption and production.
- When a question asks about "the impact on the external and internal value" it is asking for the direction of change in two separate variables, and the answer always traces one step at a time.
Common Mistakes
- Confusing 'external' and 'internal': Some candidates swap the two and think depreciation raises the external value (associating 'depreciation' with 'lower value' only in domestic terms).
- Thinking depreciation is deflationary: A common error is to assume a cheaper currency reduces import demand, so imports fall, so the domestic market faces less competition and prices fall. This is wrong in this context — the direct cost effect dominates, especially for necessary raw materials that cannot be easily substituted.
- Ignoring the qualifier: The question says "a large proportion of its raw materials". If this qualifier were absent, you could argue that the impact on the internal value might be small or zero — but here it drives the answer.
Things to Be Careful About
- The distinction between nominal depreciation (a change in the market exchange rate) and real depreciation (a change in the real exchange rate adjusted for inflation) is not needed here — the question simply says "depreciates".
- The chain is about cost-push inflation, not demand-pull. A depreciation can also increase net exports, shifting AD right and causing demand-pull inflation, but the direct cost channel is the one the question signals via "imports raw materials".
- Sign conventions: falling value of money = rising price level = inflation. Keep the direction straight.
A country's government imposes a tariff on steel imports.
What is the likely impact of this tariff on this country's economy?
Options
A It will make this country's steel exports more price competitive.
B It will lead to productive inefficiency in this country's steel industry.
C There will be an improvement in this country's terms of trade.
D There will be a decrease in producer surplus for this country's steel producers.
Reasoning
A tariff on steel imports raises the domestic price of imported steel, making domestic steel more price competitive relative to imports. This reduces competitive pressure on domestic steel producers. With less competitive discipline, there is less incentive for firms to minimise costs and operate at the lowest point on their average total cost curve. This leads to X-inefficiency and productive inefficiency (producing above minimum average cost).
Option A is incorrect: the tariff protects the domestic market but does not directly improve the price competitiveness of exports. Option C is incorrect: terms of trade (export prices/import prices) are not necessarily improved; unless the country is large enough to influence world prices, the tariff only raises domestic import prices, not affecting the terms of trade. Option D is incorrect: the tariff increases the domestic price, raising producer surplus for domestic steel producers, not decreasing it.
Answer
B
B
Background Concept
Productive efficiency occurs when a firm produces at the minimum point of its average total cost curve, meaning it cannot produce the same output at lower cost. In competitive markets, firms are forced to be productively efficient in the long run to survive; if they are not, they will be undercut by more efficient rivals. Protectionist measures such as tariffs reduce import competition, shielding domestic firms from this pressure and allowing them to operate with higher costs than necessary (X-inefficiency). This leads a deadweight loss to society because resources are not being used in their most efficient way.
Understanding the Question
The question asks for the likely impact of a tariff on steel imports on the country's economy. The four plausible options test the candidate's understanding of how tariffs affect domestic competitiveness, efficiency, terms of trade, and producer surplus. Correctly identifying the impact on efficiency requires knowledge that tariffs reduce competitive pressure, not that they directly affect exports or terms of trade.
Approach
We evaluate each option in turn. First, determine whether a tariff helps exports: typically no, because tariffs do not directly affect the price of exports unless they lead to retaliation or reduce production costs. Second, consider the effect on productive efficiency: reduced competition weakens cost-minimisation incentives, so productive inefficiency increases. Third, think about terms of trade: a tariff raises the domestic price of imports but does not change the world price (assuming a small country), so terms of trade are unaffected. Finally, consider producer surplus: a tariff raises domestic price, so domestic producers receive a higher price, increasing producer surplus, not decreasing it.
Step-by-Step Reasoning
- A tariff is a tax on imports. It raises the domestic price of imported steel above the world price, making domestic steel relatively cheaper for domestic buyers.
- This reduces the competitive pressure on domestic steel producers because they face less competition from imports at the new, higher domestic price.
- With reduced competitive pressure, domestic firms have less urgency to cut costs, innovate, or produce at minimum efficient scale. They may operate with higher costs (X-inefficiency) and produce at an output where average cost is above the minimum, leading to productive inefficiency.
- Option A: The tariff makes domestic steel relatively cheaper at home, but it does not make this country's steel exports more price competitive in foreign markets. In fact, if other countries retaliate, exports could become less competitive. So A is incorrect.
- Option C: Terms of trade = (index of export prices) / (index of import prices). The tariff raises domestic import prices paid by consumers, but the price at which the country imports (the world price) does not change unless the country is a large buyer that can influence world prices. For a small country, the world price remains unchanged, so the terms of trade are unchanged. Even for a large country, the effect is ambiguous. So C is incorrect.
- Option D: A tariff increases the domestic price of steel above the world price. Because domestic producers sell at the higher domestic price, they receive a higher price per unit. Hence producer surplus (the area above the supply curve and below the market price) increases, not decreases. So D is incorrect.
- Therefore, the only correct answer is B: the tariff leads to productive inefficiency in this country's steel industry.
Key Takeaways
- Tariffs reduce import competition, which can lead to productive inefficiency because domestic firms have less incentive to minimise costs.
- Do not confuse the domestic price impact with export competitiveness or terms of trade effects. Tariffs protect the domestic market but do not directly boost exports.
- Producer surplus for the protected industry increases because the price rises, so the statement that it decreases is wrong.
Common Mistakes
- Choosing A: Thinking that because domestic steel becomes relatively cheaper at home, it will also be cheaper abroad — but tariffs only affect domestic price of imports, not export prices.
- Choosing D: Believing that tariffs hurt domestic producers because they face higher input costs if the tariff is on an input. However, the steel tariff is on imports; domestic steel producers sell steel, so they benefit from the higher price. They may face higher input costs if steel is an input for downstream industries, but the question asks about the steel industry's own producer surplus, not downstream producers.
- Misunderstanding terms of trade: Assuming that a tariff automatically improves the terms of trade is only true for a large economy that can force foreign exporters to lower their prices, and even then the effect depends on retaliation and other factors.
Things to Be Careful About
- Always read the question precisely: 'steel imports' means the tariff is on imported steel, affecting the domestic steel market, not exports.
- Productive inefficiency is about cost minimisation; do not confuse with allocative inefficiency (price > marginal cost). The tariff also causes allocative inefficiency, but the question's correct answer focuses on productive inefficiency because of reduced competitive pressure.
- In MCQ, eliminate clearly wrong options and use economic reasoning for the remaining one.
Which measurement is not included in the calculation of the Human Development Index?
Options
A average years of schooling
B Gross National Income per capita
C infant mortality rate
D life expectancy at birth
Answer
The Human Development Index (HDI) is a composite indicator that combines three dimensions: health (life expectancy at birth), education (average years of schooling and expected years of schooling), and standard of living (Gross National Income per capita, PPP-adjusted). Infant mortality rate is not one of these components; it is a separate measure of health outcomes but not included in the HDI calculation.
C
C
Background Concept
The Human Development Index (HDI) is a composite statistic developed by the United Nations to measure a country's average achievements in three basic dimensions of human development: a long and healthy life, access to knowledge, and a decent standard of living. The specific indicators used are:
- Health: Life expectancy at birth.
- Education: Expected years of schooling (for children entering school) and mean years of schooling (for adults aged 25+).
- Standard of living: Gross National Income (GNI) per capita, adjusted for purchasing power parity (PPP).
The HDI is calculated as the geometric mean of normalized indices for each dimension. It is a widely used alternative to GDP per capita alone for comparing well-being across countries.
Understanding the Question
The question asks which of the four listed measurements is not included in the calculation of the HDI. This is a straightforward recall question. The options are:
- A: average years of schooling (part of the education dimension)
- B: Gross National Income per capita (part of the standard of living dimension)
- C: infant mortality rate (a health outcome indicator, but not used in the HDI)
- D: life expectancy at birth (part of the health dimension)
Infant mortality rate is a common measure of health, but the HDI uses life expectancy at birth instead. Therefore, C is the correct answer.
Approach
Recall the exact components of the HDI. Eliminate options that are clearly part of the HDI. The one that does not belong is the answer.
Step-by-Step Reasoning
- The HDI has three dimensions: health, education, and income.
- Health dimension: life expectancy at birth (option D).
- Education dimension: average years of schooling (option A) and expected years of schooling.
- Income dimension: GNI per capita (option B).
- Infant mortality rate (option C) is a different health indicator, often used in other indices (e.g., the Human Poverty Index or the Multidimensional Poverty Index), but not in the HDI.
- Therefore, the measurement not included is infant mortality rate.
Key Takeaways
- The HDI is a composite index of three dimensions: health, education, and income.
- The specific indicators are life expectancy, years of schooling, and GNI per capita (PPP).
- Other common development indicators (e.g., infant mortality, poverty rates, inequality measures) are not part of the HDI.
- Knowing the exact components of the HDI is a standard fact for A-Level economics.
Common Mistakes
- Confusing infant mortality rate with life expectancy: both are health indicators, but only life expectancy is used in the HDI.
- Thinking that all health-related indicators are included; the HDI uses only one health indicator.
- Forgetting that GNI per capita is PPP-adjusted in the HDI, but the question does not require that detail.
Things to Be Careful About
- The HDI has been updated over time; the current version uses the geometric mean and includes both mean and expected years of schooling. The question likely refers to the standard HDI.
- Some older versions of the HDI used GDP per capita instead of GNI, but the principle remains the same.
- Infant mortality rate is a separate indicator often used alongside the HDI, but not inside it.
The diagram shows the impact of a revaluation of a country's exchange rate on the current account of the balance of payments.
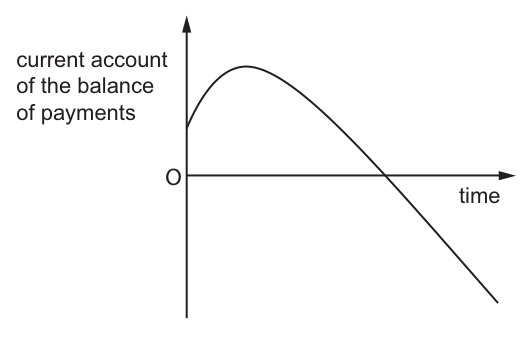
The table gives the price elasticity of demand for imports, PEDM, and the price elasticity of demand for exports, PEDX, in both the short run and the long run.
Which combination of short run and long run elasticities will give the shape shown in the diagram?
Options
| short run | long run | |||
|---|---|---|---|---|
| PEDM | PEDX | PEDM | PEDX | |
| A | 0.2 | 0.2 | 0.4 | 0.4 |
| B | 0.4 | 0.4 | 0.8 | 0.8 |
| C | 0.8 | 0.8 | 1.2 | 1.2 |
| D | 1.2 | 1.2 | 1.6 | 1.6 |
Working
A revaluation (appreciation) makes exports more expensive to foreign buyers and imports cheaper for domestic residents. In the short run, if demand is price inelastic (PED < 1), the price effect dominates: export revenue rises and import spending falls, improving the current account balance. In the long run, demand becomes price elastic (PED > 1), so the quantity effect dominates: export volumes fall significantly and import volumes rise significantly, worsening the current account balance. The diagram shows an initial improvement (movement into surplus) followed by deterioration (movement into deficit), which requires short-run inelastic demand and long-run elastic demand. Only option B has PED values below 1 in the short run (0.4) and above 1 in the long run (0.8).
Answer
B
B
Background Concept
When a country revalues its currency (the exchange rate appreciates), its exports become more expensive in foreign markets and imports become cheaper in the domestic market. The impact on the current account of the balance of payments depends on the price elasticity of demand for exports (PEDX) and imports (PEDM).
The Marshall-Lerner condition states that a change in the exchange rate will improve the trade balance only if the sum of the absolute values of PEDX and PEDM is greater than 1. However, this condition applies in the long run when quantities have time to adjust. In the short run, demand tends to be price inelastic because consumers and firms have established habits, existing contracts are in place, and there are few immediate substitutes. This gives rise to the J-curve effect (or, for a revaluation, an inverted J-curve):
- Short run: With inelastic demand (PED < 1), the price effect dominates. A revaluation raises the domestic currency price of imports and the foreign currency price of exports. Because quantities do not adjust much immediately, the value of imports falls (cheaper per unit, and quantity barely rises) and the value of exports rises (more domestic currency per unit sold, and quantity barely falls). The current account improves.
- Long run: With elastic demand (PED > 1), the quantity effect dominates. Consumers and firms have time to switch away from now more expensive exports and toward cheaper imports. Export volumes fall significantly and import volumes rise significantly. The current account deteriorates.
Understanding the Question
The question presents a diagram showing the current account balance over time following a revaluation. The curve starts at the origin (balanced current account), rises into surplus, then falls, crosses the time axis into deficit, and continues falling. The table provides four combinations of short-run and long-run PEDM and PEDX values. The task is to identify which combination of elasticities produces the pattern shown in the diagram.
The diagram depicts an initial improvement in the current account (surplus) followed by a deterioration (deficit). This is the characteristic pattern for a revaluation when demand is inelastic in the short run and elastic in the long run. The question tests whether you can match this pattern to the correct elasticity values.
Approach
To solve this, apply the following logic:
- Identify the pattern: Initial improvement (surplus) then deterioration (deficit).
- Determine the elasticity requirements: Short-run PED values must be less than 1 (inelastic) so the price effect dominates and the current account improves. Long-run PED values must be greater than 1 (elastic) so the quantity effect dominates and the current account deteriorates.
- Check each option against these criteria.
Step-by-Step Reasoning
Step 1: Analyse the diagram
The current account starts at zero (balanced), rises into surplus, then falls into deficit. This means the revaluation initially improves the current account before it worsens.
Step 2: Apply elasticity theory
- In the short run, for the current account to improve after a revaluation, demand for both exports and imports must be price inelastic (PED < 1). When the currency appreciates, export prices in foreign currency rise and import prices in domestic currency fall. If demand is inelastic, the percentage change in quantity demanded is smaller than the percentage change in price. Therefore, the value of exports rises (higher price × barely lower quantity) and the value of imports falls (lower price × barely higher quantity), improving the trade balance.
- In the long run, demand must become price elastic (PED > 1). Consumers and producers have time to adjust their behaviour, find alternatives, and switch suppliers. The percentage change in quantity demanded now exceeds the percentage change in price. Export volumes fall sharply and import volumes rise sharply, so the value of exports falls and the value of imports rises, worsening the trade balance.
Step 3: Evaluate the options
- Option A: Short run 0.2 and 0.4 (both inelastic), long run 0.4 and 0.8 (both still inelastic). The long-run values are not elastic enough to cause the observed deterioration into deficit.
- Option B: Short run 0.4 and 0.4 (both inelastic, sum = 0.8 < 1), long run 0.8 and 0.8 (both elastic, sum = 1.6 > 1). This matches the required pattern: short-run improvement followed by long-run deterioration.
- Option C: Short run 0.8 and 0.8 (both elastic, sum = 1.6 > 1). If demand is already elastic in the short run, the revaluation would cause an immediate deterioration of the current account, not an initial improvement.
- Option D: Short run 1.2 and 1.2 (both elastic). Again, this would cause immediate deterioration, not the initial surplus shown.
Conclusion: Only Option B satisfies the condition of short-run inelastic demand (PED < 1) and long-run elastic demand (PED > 1).
Key Takeaways
- A revaluation (appreciation) improves the current account in the short run only if demand for exports and imports is price inelastic.
- In the long run, as demand becomes price elastic, the current account deteriorates.
- The Marshall-Lerner condition (PEDX + PEDM > 1) determines the long-run outcome of an exchange rate change.
- The J-curve diagram for a revaluation is the mirror image of the standard J-curve for a devaluation.
Common Mistakes
- Confusing revaluation with devaluation: A devaluation (depreciation) produces the opposite J-curve pattern—initial deterioration followed by improvement. Choosing elastic short-run values would be correct for a devaluation, not a revaluation.
- Ignoring the threshold of 1: Students sometimes forget that the critical value is PED = 1. Values below 1 are inelastic (price effect dominates); values above 1 are elastic (quantity effect dominates).
- Misreading the diagram: The diagram clearly shows an initial rise to surplus, not an initial fall. Any option with short-run elasticities above 1 can be eliminated immediately.
Things to Be Careful About
- Always check whether the question concerns a revaluation (appreciation) or devaluation (depreciation), as the J-curve pattern is reversed.
- Ensure you are comparing the absolute values of PED to 1; the sign is negative for both imports and exports (law of demand), but we use absolute values when discussing elasticity magnitude.
- The diagram shows the current account balance, not the trade balance specifically, but for this question the same elasticity principles apply to the visible trade component that drives the current account.
What is not a function of the International Monetary Fund (IMF)?
Options
A to encourage exchange rate stability
B to provide financial assistance for a country with failed economic policies
C to provide funds for a water purifying plant in a developing country
D to provide loans for countries following a natural disaster
Answer
The IMF's primary functions are to promote international monetary cooperation, exchange rate stability, and provide temporary financial assistance to countries facing balance of payments difficulties. It does not fund specific infrastructure projects like a water purifying plant. That is the role of the World Bank. Therefore, option C is not a function of the IMF.
C
Background Concept
The International Monetary Fund (IMF) and the World Bank are two distinct international financial institutions created at the Bretton Woods Conference in 1944, but they have different purposes. The IMF's core mission is to ensure the stability of the international monetary system. It does this by monitoring exchange rates, providing short-term loans to countries with balance of payments crises, and offering policy advice. The World Bank, on the other hand, is a development bank focused on reducing poverty and promoting long-term economic development by funding specific projects (like infrastructure, education, and health) in developing countries.
Understanding the Question
This is a multiple-choice question asking which of the four listed activities is NOT a function of the IMF. The question tests your knowledge of the specific roles of the IMF versus other international bodies, particularly the World Bank. Each option describes a type of financial or policy action, and you must identify the one that falls outside the IMF's mandate.
Approach
Recall the IMF's primary functions: exchange rate surveillance, providing short-term loans to address balance of payments problems, and offering technical assistance. Then, for each option, ask: "Is this something the IMF does?" If it sounds like a long-term development project, it is likely the World Bank's job. Option C is the clear outlier.
Step-by-Step Reasoning
-
Option A: to encourage exchange rate stability. This is a core function of the IMF. It monitors the exchange rate policies of its member countries and provides a forum for cooperation to maintain a stable system of exchange rates. This is correct.
-
Option B: to provide financial assistance for a country with failed economic policies. This is a classic IMF role. When a country faces a balance of payments crisis due to poor economic management, the IMF provides loans conditional on the country implementing structural reforms (austerity, deregulation, etc.) to restore stability. This is correct.
-
Option C: to provide funds for a water purifying plant in a developing country. This is a specific infrastructure project. The IMF does not fund individual projects. This is the role of the World Bank (specifically the International Bank for Reconstruction and Development or the International Development Association). This is NOT a function of the IMF.
-
Option D: to provide loans for countries following a natural disaster. The IMF does provide emergency financial assistance to countries hit by natural disasters through facilities like the Rapid Financing Instrument (RFI) or the Rapid Credit Facility (RCF). These are short-term, low-conditionality loans to help with immediate balance of payments needs. This is correct.
Since options A, B, and D are all functions of the IMF, the only one that is not is C.
Key Takeaways
- The IMF focuses on the stability of the international monetary system and provides short-term, conditional loans for balance of payments crises.
- The World Bank focuses on long-term economic development and funds specific projects (infrastructure, health, education).
- A common exam trick is to confuse the two institutions. Remember: IMF = monetary stability; World Bank = development projects.
Common Mistakes
- Confusing the IMF with the World Bank: This is the most common error. Students often think the IMF funds development projects because both institutions are involved in lending to countries.
- Not knowing about emergency facilities: Some students might incorrectly think the IMF does not provide disaster relief (option D), but it does, through specific rapid financing instruments.
Things to Be Careful About
- Read the question carefully: it asks for what is not a function.
- Do not overthink. The distinction between the IMF and World Bank is a standard piece of syllabus knowledge.
- Remember that the IMF's loans are typically conditional and aimed at macroeconomic stability, not micro-level projects.
The diagram shows the effect of trade creation if a tariff is removed.
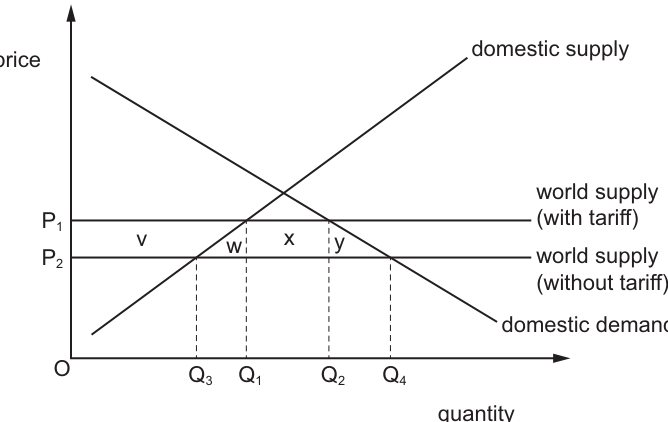
Which areas show the total net gain to the domestic economy?
Options
A v, w, x and y
B v, w and x only
C w and x only
D w and y only
Answer
D
Removing the tariff lowers the price from P1 to P2. The total net gain to the domestic economy is the efficiency gain, which equals the production efficiency gain (w) plus the consumption efficiency gain (y). Area v is a transfer from producers to consumers, and area x is a transfer from the government (lost tariff revenue) to consumers. These transfers cancel out in aggregate and do not represent a net gain to the domestic economy as a whole.
D
Background Concept
Trade creation occurs when a country removes a tariff (or other trade barrier) and switches from higher-cost domestic production to lower-cost imports. This reallocation of resources increases overall economic welfare.
In a standard partial-equilibrium trade diagram:
- The domestic supply curve shows the marginal cost of producing domestically.
- The domestic demand curve shows the marginal benefit to consumers.
- The world supply line shows the price at which the country can buy imports.
- A tariff raises the domestic price above the world price (from P2 to P1), protecting domestic producers but creating deadweight losses.
When the tariff is removed, the price falls to the world level P2. This changes the welfare of three groups: consumers (gain), producers (lose), and the government (loses tariff revenue). The net effect on the domestic economy depends on whether the gains exceed the losses.
Understanding the Question
The question asks which areas represent the total net gain to the domestic economy when a tariff is removed. The phrase "total net gain" is crucial: it requires considering the economy as a whole (consumers + producers + government), not just one group. A net gain is an efficiency improvement—a deadweight loss that is eliminated—not merely a transfer of income from one group to another.
The diagram shows four labelled areas between the two price levels (P1 and P2):
- v: a rectangle between Q3 and Q1.
- w: a triangle between the domestic supply curve and P2, from Q3 to Q1.
- x: a rectangle between Q1 and Q2.
- y: a triangle between the domestic demand curve and P2, from Q2 to Q4.
Approach
To determine the net gain, we can either:
- Calculate the change in total surplus (consumer surplus + producer surplus + government revenue), or
- Identify the efficiency gains directly from the diagram.
Method 1:
- Consumer surplus increases by the entire area between P1 and P2 up to Q4: v + w + x + y.
- Producer surplus decreases by area v (the surplus lost on units Q3 to Q1 that are no longer produced domestically).
- Government revenue decreases by area x (the tariff revenue previously collected on imports Q1 to Q2).
- Net gain = (v + w + x + y) - v - x = w + y.
Method 2:
- w is the production efficiency gain: the cost saving from no longer producing units Q3 to Q1 domestically at a higher marginal cost than the world price P2.
- y is the consumption efficiency gain: the value of additional consumption from Q2 to Q4, where the marginal benefit (demand curve) exceeds the marginal cost (P2).
Both methods yield w + y.
Step-by-Step Reasoning
Step 1: Effect on consumer surplus
When the price falls from P1 to P2, consumers benefit in two ways:
- On the units they already bought (up to Q2), they pay P2 instead of P1, gaining surplus equal to the rectangle between P1 and P2. This includes areas v (on units Q3 to Q1 that switch from domestic to imported) and x (on units Q1 to Q2 that were previously imported with tariff).
- On the additional units they now buy (from Q2 to Q4), they gain surplus equal to area y, the triangle between the demand curve and P2.
Total consumer surplus gain = v + w + x + y.
Step 2: Effect on producer surplus
Domestic producers lose because they now receive P2 instead of P1, and they reduce output from Q1 to Q3. They lose the surplus they previously earned on the units between Q3 and Q1. This loss is area v.
Step 3: Effect on government revenue
The government previously collected a tariff of (P1 - P2) on each unit imported (Q2 - Q1). This revenue is area x. When the tariff is removed, this revenue disappears.
Step 4: Aggregate effect on the domestic economy
The domestic economy comprises consumers, producers, and the government. The net change is:
Gain in CS + Change in PS + Change in GR
= (+v + w + x + y) + (-v) + (-x)
= w + y.
Area w represents the production efficiency gain: resources are freed from domestic production where marginal cost exceeded P2 and are instead used for imports at P2.
Area y represents the consumption efficiency gain: consumers value the additional units (Q2 to Q4) more than the world price P2.
Areas v and x are mere transfers of purchasing power:
- v transfers from producers to consumers.
- x transfers from the government (and ultimately taxpayers) to consumers.
Transfers do not change the total size of the economic surplus; they only change its distribution.
Key Takeaways
- The net welfare gain from trade creation is the sum of the production efficiency gain (w) and the consumption efficiency gain (y).
- Transfers (v and x) are not net gains to the domestic economy as a whole, even though they benefit specific groups.
- When evaluating welfare changes, always account for all affected groups: consumers, producers, and the government.
- The net gain equals the deadweight loss triangles that are eliminated by removing the tariff.
Common Mistakes
- Including v or x in the net gain: Students often add all areas between P1 and P2, forgetting that v and x are transfers, not efficiency gains.
- Forgetting the government: Some calculate only the consumer gain minus the producer loss, omitting the lost tariff revenue (x).
- Confusing trade creation with trade diversion: Trade creation involves switching from expensive domestic production to cheap imports. Trade diversion involves switching from cheap imports outside a trade bloc to more expensive imports from within the bloc. This question is about trade creation.
- Misidentifying the areas: Confusing which area represents the production efficiency gain versus the transfer from producers.
Things to Be Careful About
- The domestic economy includes the government: Tariff revenue is a benefit to the domestic economy (used for public spending or tax cuts). Its loss is a cost.
- Transfers vs. efficiency gains: Rectangles (v and x) typically represent transfers in trade diagrams; triangles (w and y) typically represent efficiency gains (deadweight losses).
- Direction of the shift: Removing a tariff lowers the price, so check that you are analyzing the move from P1 to P2, not the reverse.
- The question asks for the domestic economy, not just consumers: If the question asked for the gain to consumers alone, the answer would be v + w + x + y. But for the domestic economy as a whole, transfers cancel out.
What is most likely to prevent a developing country from achieving economic development?
Options
A increased allocation of resources to production of goods that have a high income elasticity of demand
B increased government legislation for the protection of employment
C increased tax allowances on firms investing in research and development
D the decision of developed countries to increase quotas for goods produced by developing countries
Increased government legislation for the protection of employment, such as strict job security laws, high minimum wages, and restrictions on hiring and firing, reduces labour market flexibility. This raises firms' costs, discourages investment and innovation, and can lead to inefficiency and higher unemployment, particularly in developing countries where labour-intensive production is key. Such rigidities are most likely to prevent the structural transformation and productivity growth necessary for economic development.
Answer
B
B
Background Concept
Economic development involves improvements in living standards, health, education, and economic structure, moving from low-income, agrarian economies to higher-income, industrialised and service-based economies. Key determinants include investment in physical and human capital, technological progress, institutional quality, and policies that foster flexibility and competition. Government intervention can play a role in correcting market failures, but poorly designed or excessive regulation can lead to government failure, hindering development.
Understanding the Question
The question asks which option is most likely to prevent a developing country from achieving economic development. It presents four different policies or events. The task is to identify the one that would impede development, not accelerate it. The correct answer B involves increased government legislation to protect employment – this typically means stricter rules on hiring and firing, minimum wages, and job security, which can make labour markets rigid.
Approach
Evaluate each option in turn, considering its likely impact on economic development in a developing country. Look for the option that creates the most significant obstacles to growth and structural change. Eliminate options that would likely support development (C, D) or have ambiguous effects (A) that are less likely to be damaging than B.
Step-by-Step Reasoning
- Option B (correct): Increased employment protection legislation makes it harder for firms to adjust their workforce, reduces flexibility, and increases labour costs. In developing countries, where many workers are in informal sectors or where labour-intensive manufacturing is key to growth, such legislation can discourage foreign direct investment, reduce competitiveness, and slow down the reallocation of labour from low-productivity agriculture to higher-productivity industry. This directly impedes economic development.
- Option A: Increased allocation of resources to production of goods with high income elasticity of demand. As global incomes rise, demand for these goods grows. This could boost exports and income for the developing country, supporting development. It may involve a shift in production towards higher-value goods, which is generally positive. Thus it is unlikely to prevent development.
- Option C: Increased tax allowances on R&D investment encourage innovation and technological progress, which are key drivers of development. This policy would likely promote economic growth and structural change, not prevent it.
- Option D: The decision of developed countries to increase quotas for goods produced by developing countries increases market access, allowing developing countries to export more, earn foreign exchange, and benefit from economies of scale. This would foster development, not hinder it.
Therefore, B is the only option that creates a significant barrier to development.
Key Takeaways
- Not all government intervention helps development; excessive regulation can be a form of government failure.
- Labour market flexibility is often crucial for developing countries to attract investment and facilitate structural change.
- Trade liberalisation and R&D incentives generally promote development.
- Be able to evaluate policies in the specific context of developing economies.
Common Mistakes
- Confusing the effect of a policy: some might think that employment protection helps workers and therefore helps development, but overshooting on protection can harm overall productivity and growth.
- Assuming that increased quotas by developed countries are harmful; in fact, they increase export opportunities for developing countries.
- Misunderstanding income elasticity: goods with high income elasticity can be a growth opportunity.
- Failing to weigh relative impacts: all options except B are supportive or neutral for development.
Things to Be Careful About
- Distinguish between economic growth and economic development: development is broader, but here the policies affect both.
- Consider the specific characteristics of developing countries: large informal sectors, labour-intensive production, institutional weaknesses.
- Not all regulation is bad; the question asks “most likely to prevent”, so identify the most damaging.
- Read each option carefully: “increased tax allowances” is a tax incentive, not a tax increase.
Your score so far
Answer a question to start scoring
Your marks add up here as you work through the paper.